
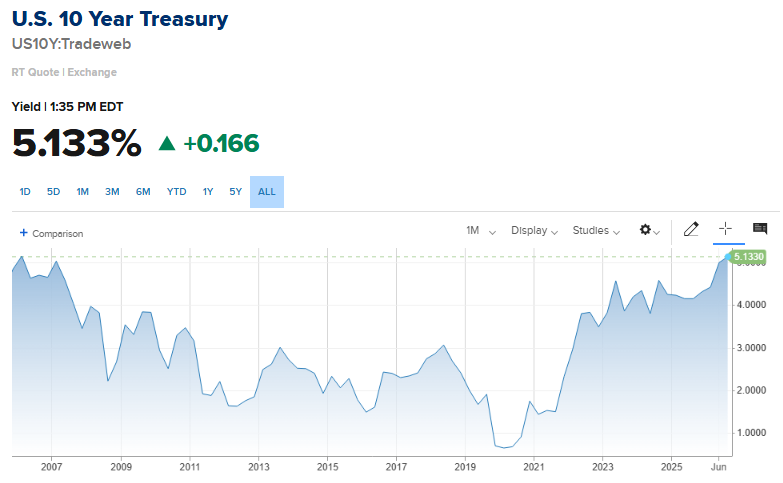
U.S. 10‑Year Treasury Yield Breaks 5.13%: Implications for Quantitative Strategies
Research preview
The 10‑year Treasury yield has surged past 5.13%, a level not seen since the pre‑crisis rally of the mid‑2000s. This move reshapes the risk‑free benchmark that underpins most quantitative models, forcing traders to reassess portfolio construction, factor exposures, and risk management. The following analysis explores the drivers of the yield jump, its impact on common quantitative signals, and practical steps to adjust strategies in real time. Why the Yield Spike Matters for Quant Models Most systematic frameworks treat the risk‑free rate as a static input or update it with a lag of a few days. A sudden increase of a full percentage point compresses the spread between risky assets and...
Client research
Register free or login to read the full report
Registration is free. The full report includes chart snapshots, level work, technical tables, catalyst context, and the complete desk read.
Chat with XTRSK
Chat ready
Start a chat and the XTRSK team will be notified immediately.