
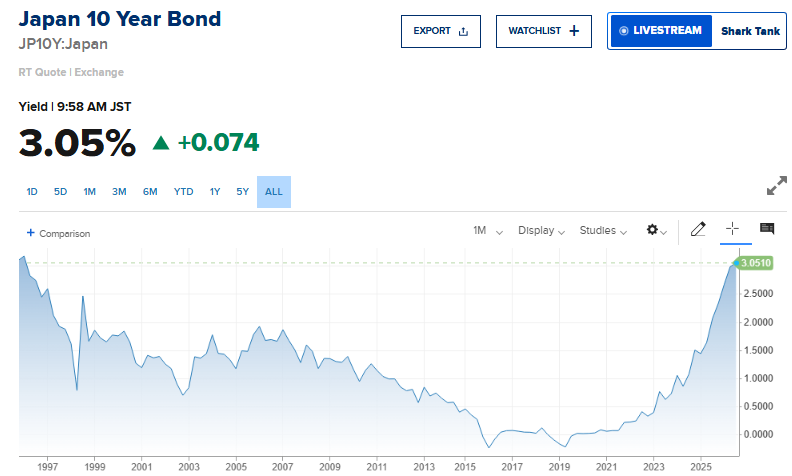
Japan’s 10‑Year Yield Surge: What Quant Traders Should Model and Trade
Research preview
Japan’s 10‑year government bond yield has leapt to its highest level in more than three decades. The move reshapes the risk‑free benchmark that underpins virtually every Japanese‑denominated model, from discount‑factor curves to equity‑valuation multiples. This article explains the mathematical foundations that quantify the impact of a sudden yield jump, illustrates common modelling pitfalls, and offers concrete steps for a quantitative trading desk to adjust its strategies. Why the Yield Curve Matters for Quant Strategies The risk‑free rate is a core input to any pricing or risk model. A higher 10‑year yield lifts the entire forward curve, increasing discount rates used for cash‑flow valuation and altering implied volatilities in option pricing....
Client research
Register free or login to read the full report
Registration is free. The full report includes chart snapshots, level work, technical tables, catalyst context, and the complete desk read.
Chat with XTRSK
Chat ready
Start a chat and the XTRSK team will be notified immediately.