
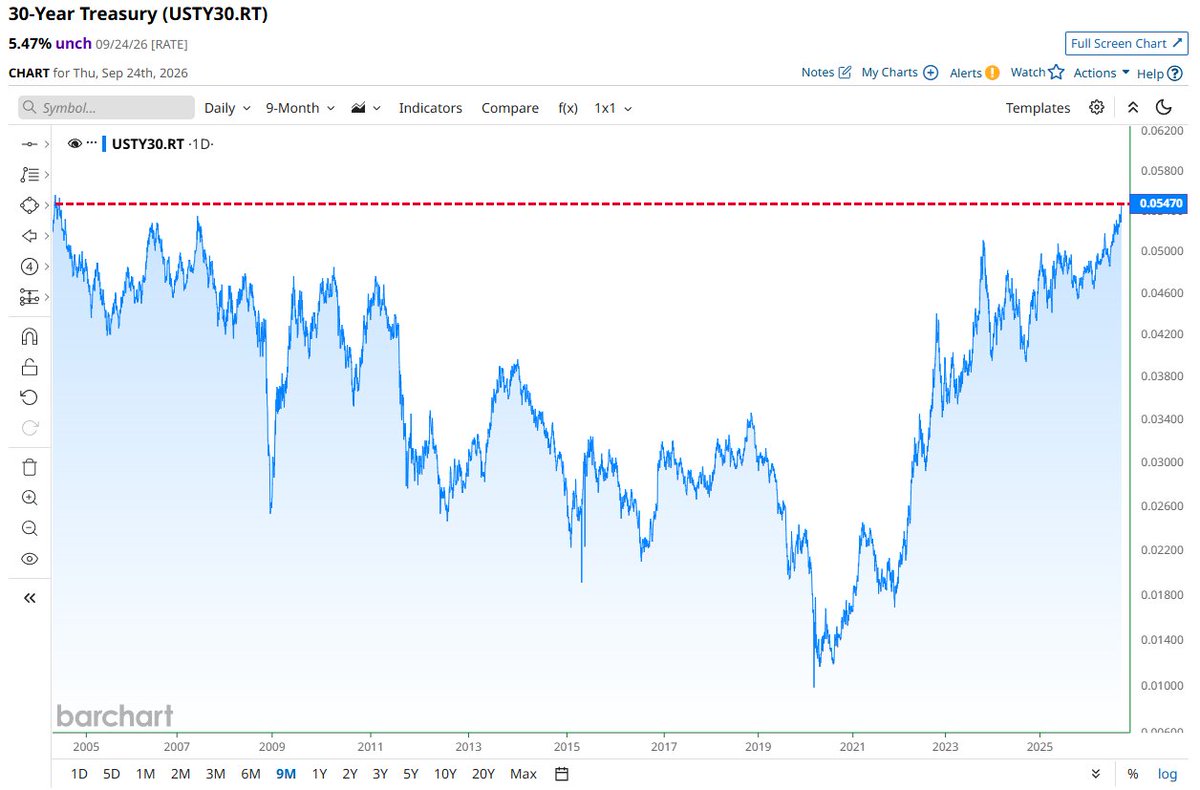
Treasury Yield Spike Highlights Need for High‑Dimensional Machine‑Learning Models in Fixed‑Income Trading
Research preview
The 30‑year Treasury yield closed at 5.47 %, the highest level seen since 2004. Such a move reshapes the risk‑free benchmark that underpins valuation, hedging, and portfolio construction across asset classes. For quantitative traders, the event underscores why modern high‑dimensional statistical tools are essential for extracting signal from a flood of macro, market, and alternative data. Why Traditional Factor Models Struggle with Yield Surges Classical term‑structure models often rely on a handful of macro variables—GDP growth, inflation expectations, and the short‑rate policy path—to explain movements in long‑dated yields. When yields jump sharply, the residuals of these low‑dimensional regressions tend to explode, indicating omitted variables or non‑linear dynamics....
Client research
Register free or login to read the full report
Registration is free. The full report includes chart snapshots, level work, technical tables, catalyst context, and the complete desk read.
Chat with XTRSK
Chat ready
Start a chat and the XTRSK team will be notified immediately.