
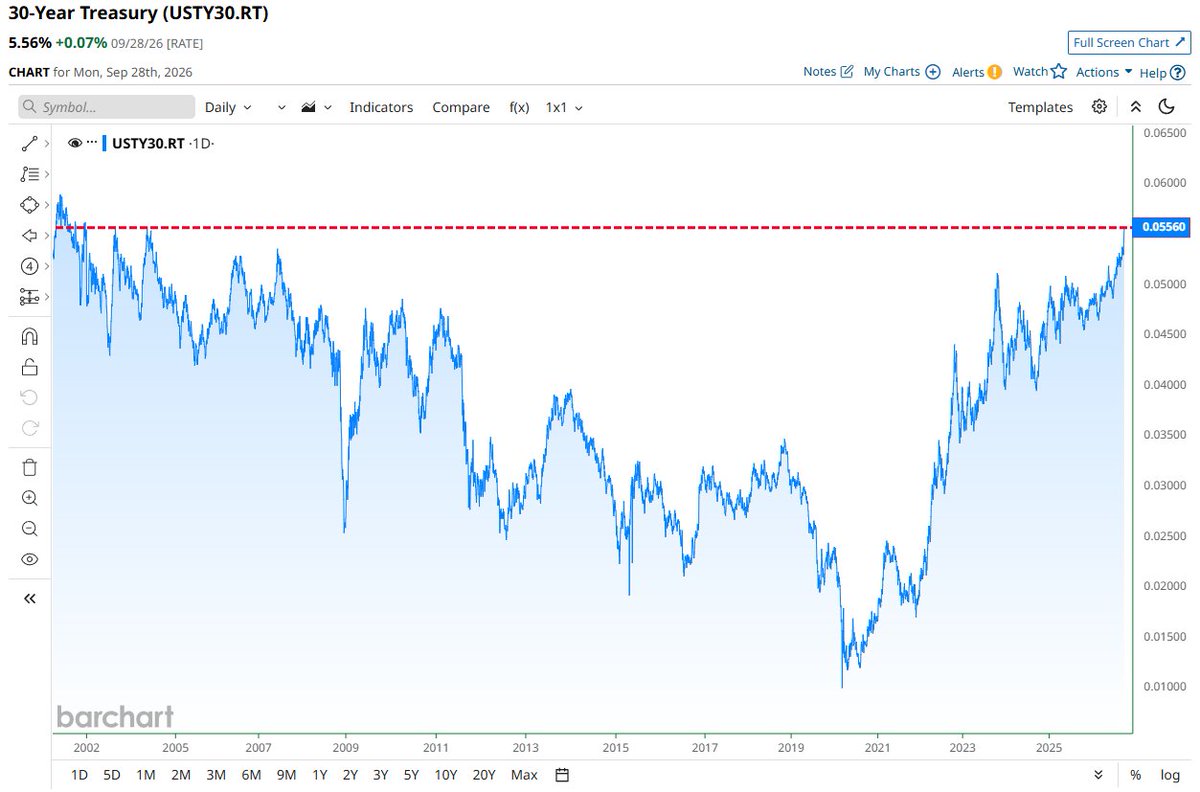
How the 30‑Year Treasury Yield Spike Impacts Quantitative Trading Strategies
Research preview
The 30‑year U.S. Treasury yield has surged to 5.56%, a level not seen since 2003. This unprecedented move reshapes the risk‑free benchmark that underpins many quantitative models. In this article we explore why the yield matters, how it alters key metrics such as the Sharpe ratio, and what traders can do to adapt their portfolios. The Yield as the New Risk‑Free Anchor The risk‑free rate is a cornerstone of modern portfolio theory, serving as the baseline for expected returns and for discounting cash flows....
Client research
Register free or login to read the full report
Registration is free. The full report includes chart snapshots, level work, technical tables, catalyst context, and the complete desk read.
Chat with XTRSK
Chat ready
Start a chat and the XTRSK team will be notified immediately.