
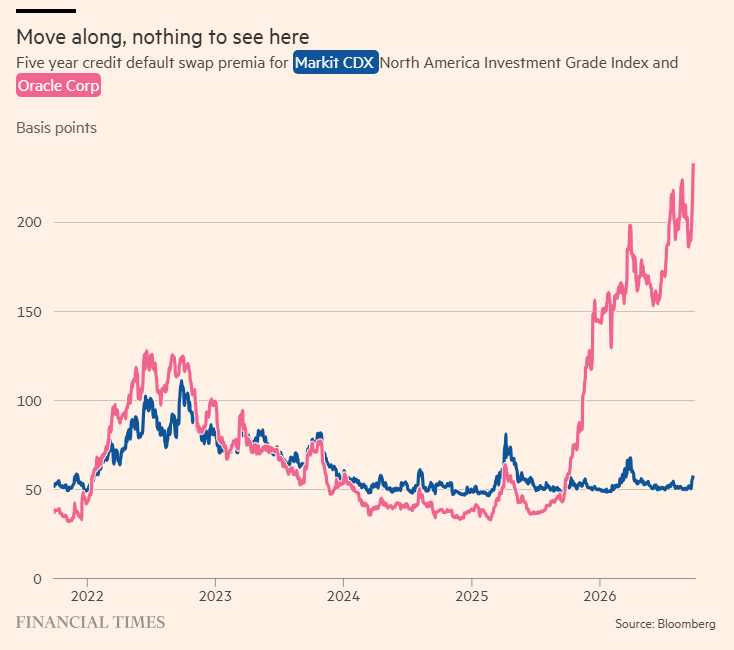
Oracle CDS Spike Signals Risk: How Machine Learning Can Spot Credit Stress Early
Research preview
Oracle’s credit default swaps have surged to an all‑time high, putting the software giant a single downgrade away from junk status. For quantitative traders, this event is a reminder that credit markets can move sharply on information that may be hidden in high‑dimensional data. In this article we explain why the CDS jump matters, review the statistical pitfalls of high‑dimensional modelling, and outline a machine‑learning workflow that can help detect similar credit‑risk buildups before they fully materialise. Why a CDS Spike Matters A credit default swap price reflects the market’s assessment of the probability that a firm will default within a given horizon....
Client research
Register free or login to read the full report
Registration is free. The full report includes chart snapshots, level work, technical tables, catalyst context, and the complete desk read.
Chat with XTRSK
Chat ready
Start a chat and the XTRSK team will be notified immediately.