
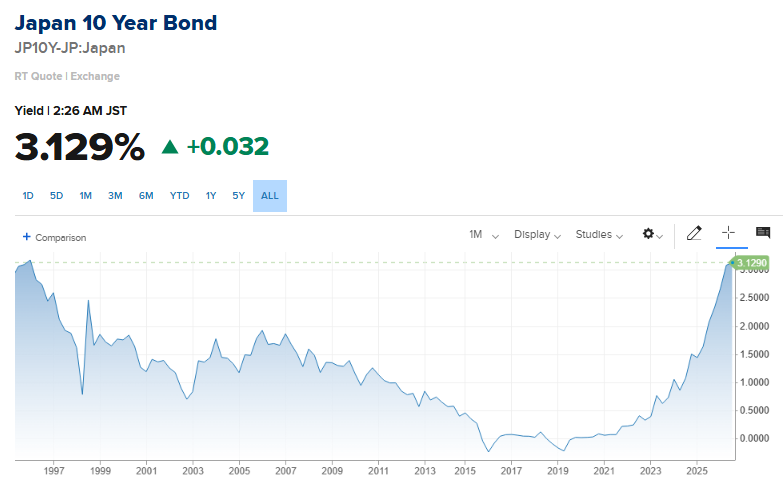
Japan’s 10‑Year Yield Hits 30‑Year High – Implications for Quant Strategies
Research preview
Japan’s 10‑year government bond yield has surged to a level not seen in more than three decades. The move reflects shifting monetary policy expectations and global rate dynamics, creating new opportunities and risks for quantitative traders. This article dissects the drivers, quant‑model considerations, and practical steps to adjust your strategies. Why the Yield Spike Matters The 10‑year Japanese yield is a benchmark for a wide range of fixed‑income instruments, from sovereign bonds to corporate credit spreads. When the yield climbs, the price of existing bonds falls, altering the risk‑adjusted returns of many strategies that rely on carry, duration, or relative value....
Client research
Register free or login to read the full report
Registration is free. The full report includes chart snapshots, level work, technical tables, catalyst context, and the complete desk read.
Chat with XTRSK
Chat ready
Start a chat and the XTRSK team will be notified immediately.