
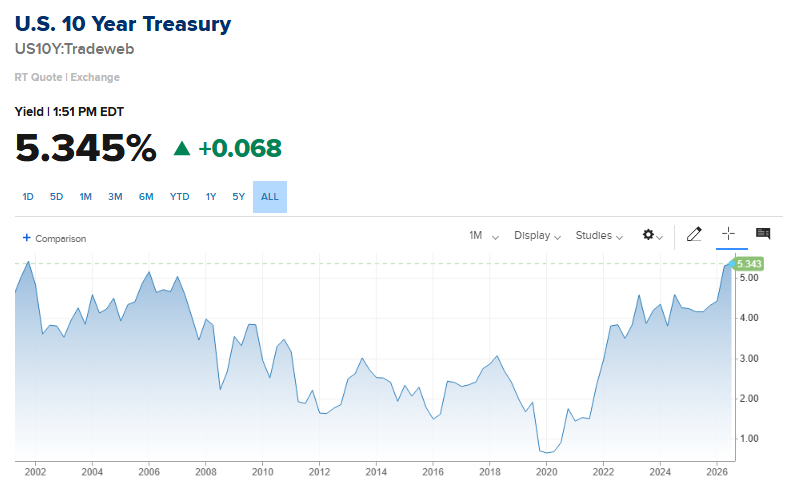
How the 10‑Year Treasury Spike Reshapes Quantitative Trading Strategies
Research preview
The U.S. 10‑year Treasury yield has surged to its highest level in more than two decades, a move that reverberates through every corner of the fixed‑income market. For quantitative traders, this event forces a reassessment of risk models, carry trades, and the interaction between sovereign rates and equity‑related signals. Yield Dynamics and Macro Context The recent breakout above the previous 24‑year peak reflects a combination of tighter monetary policy, rising inflation expectations, and robust fiscal financing needs. When sovereign yields climb, the risk‑free benchmark used in virtually all Sharpe‑ratio calculations also rises, compressing the excess return available to risk‑taking strategies....
Client research
Register free or login to read the full report
Registration is free. The full report includes chart snapshots, level work, technical tables, catalyst context, and the complete desk read.
Chat with XTRSK
Chat ready
Start a chat and the XTRSK team will be notified immediately.