
How Brazil’s Record‑Breaking Rally Highlights Correlation Risk and Portfolio Construction
Research preview
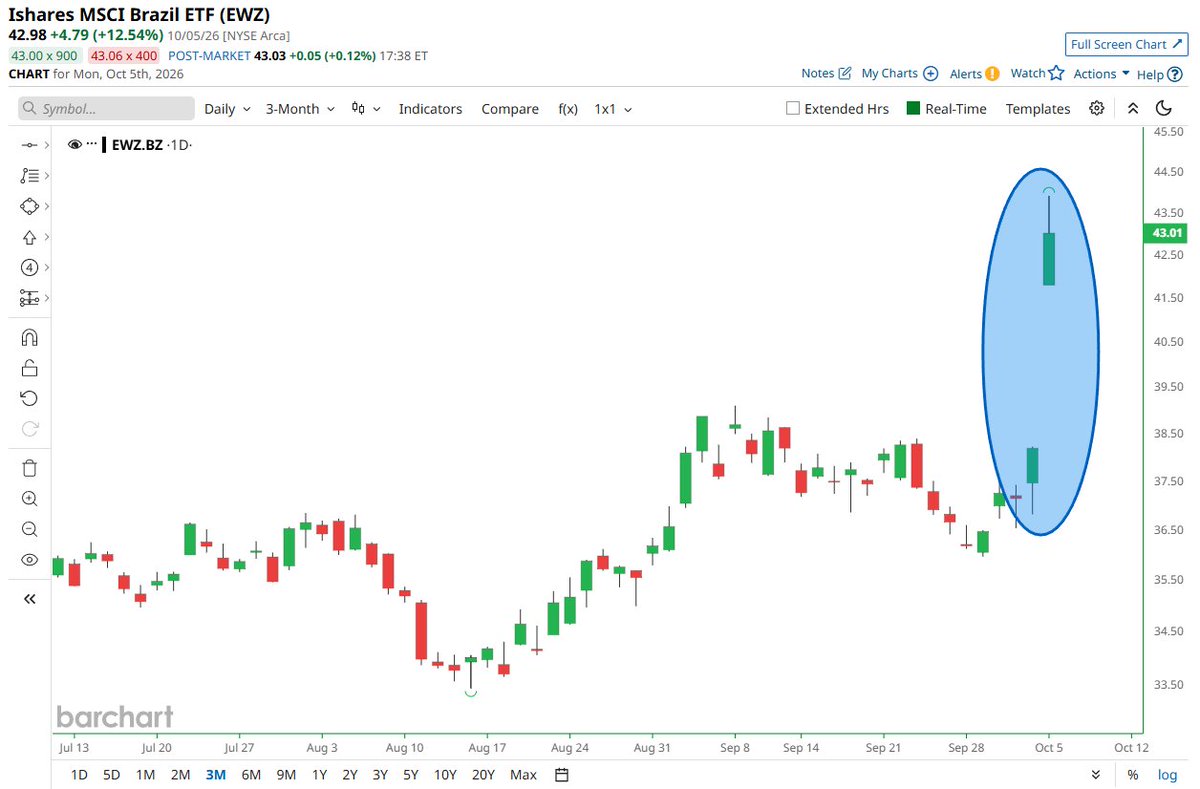
The Brazilian equity market posted its strongest single‑day gain in more than six years, a move that caught many traders who bought call options last month. This surge provides a vivid case study for quantitative investors on how extreme market events interact with portfolio volatility, correlation, and risk‑adjusted returns. The following analysis connects the rally to core finance theory and shows how to embed such insights into systematic trading models. The Market Shock and Its Immediate Impact On the day of the rally, the main Brazilian index jumped well above its recent average, delivering a return that dwarfed typical daily moves....
Client research
Register free or login to read the full report
Registration is free. The full report includes chart snapshots, level work, technical tables, catalyst context, and the complete desk read.
Chat with XTRSK
Chat ready
Start a chat and the XTRSK team will be notified immediately.