
How the S&P 500’s Record Surge Highlights Core Quantitative Finance Concepts
Research preview
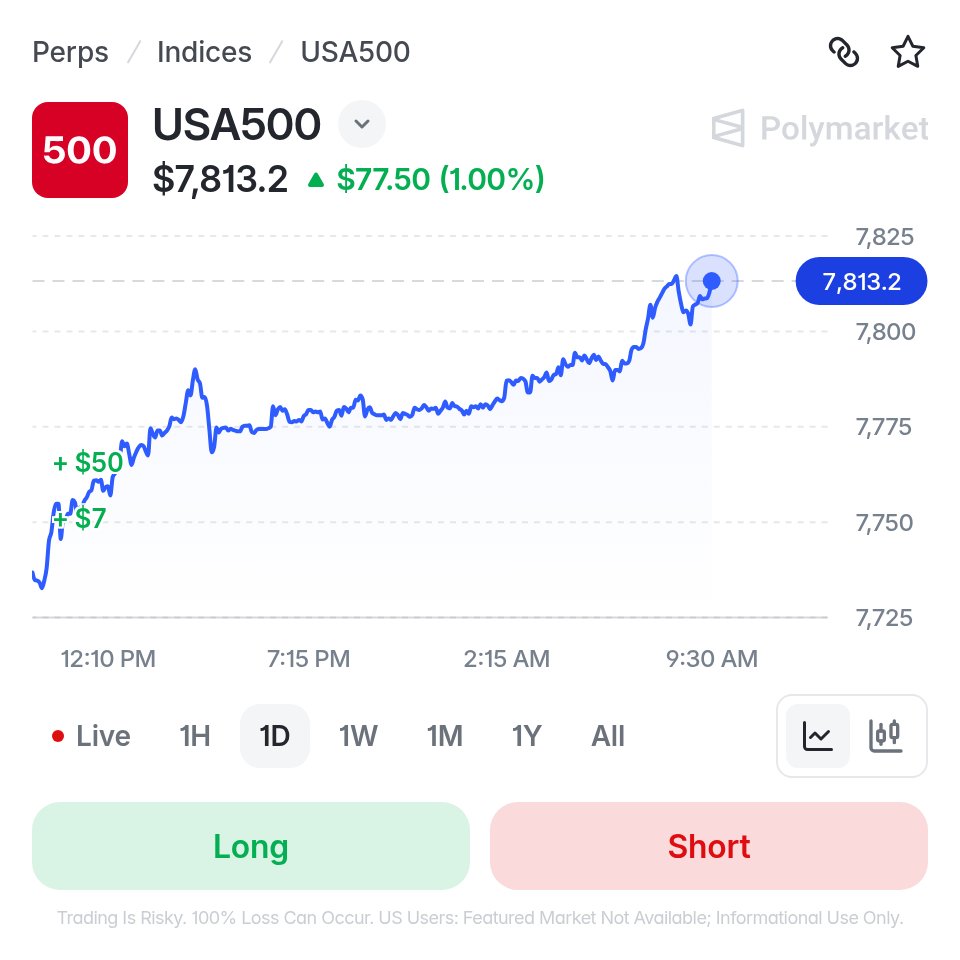
The S&P 500 recently broke through the 7,800 level, setting a new intraday high. Such moves are more than market headlines; they provide a live laboratory for the quantitative techniques taught in graduate finance programs. This article connects the rally to key models, risk measures, and practical tools that students learn in advanced courses. Momentum, Mean Reversion, and the Role of Stochastic Models When a broad index climbs sharply, two opposing forces often dominate the subsequent price path. Momentum models suggest the up‑trend will continue, while mean‑reversion frameworks anticipate a pull‑back toward a long‑run average. Stochastic differential equations, covered in courses on Brownian motion and stochastic calculus, formalize these ideas....
Client research
Register free or login to read the full report
Registration is free. The full report includes chart snapshots, level work, technical tables, catalyst context, and the complete desk read.
Chat with XTRSK
Chat ready
Start a chat and the XTRSK team will be notified immediately.