
How the 30‑Year Treasury Yield Spike Shapes Quantitative Trading Strategies
Research preview
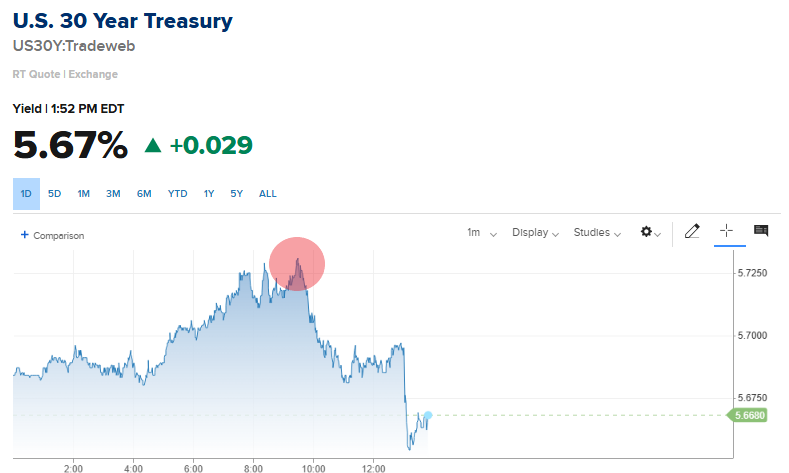
The 30‑year U.S. Treasury yield surged to 5.73%, a level not seen in more than two decades. This move reshapes the risk‑free benchmark that underpins virtually every quantitative model. In the following sections we explore why the yield jumped, how it alters the fundamentals of asset pricing, what it means for common factor models, and how traders can adjust their frameworks to stay ahead. The Drivers Behind the Yield Surge The long‑term Treasury rate reflects expectations of future inflation, fiscal deficits, and the supply‑demand balance for safe assets. Recent data releases showed higher core CPI numbers and a tightening fiscal stance, prompting investors to demand a larger term premium....
Client research
Register free or login to read the full report
Registration is free. The full report includes chart snapshots, level work, technical tables, catalyst context, and the complete desk read.
Chat with XTRSK
Chat ready
Start a chat and the XTRSK team will be notified immediately.