
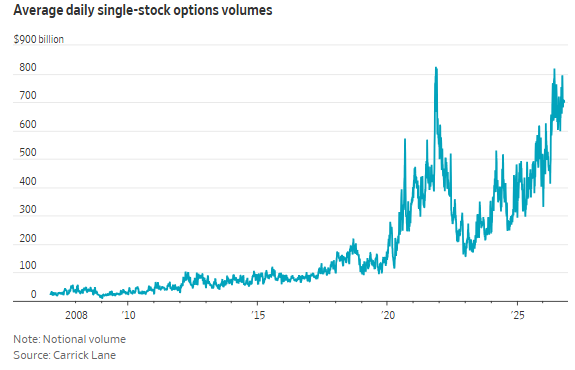
Single‑Stock Option Volume Hits Near‑Record Levels – Implications for Quantitative Traders
Research preview
Option activity has surged to its highest point since the meme‑driven frenzy of 2021. This unprecedented flow raises questions about market liquidity, pricing efficiency, and the reliability of traditional asset‑pricing models. Quantitative traders need to reassess risk, execution costs, and signal extraction in an environment where option volume is exploding. Why Option Volume Matters for Asset Pricing When traders buy or sell options in large quantities, the underlying stock’s implied volatility surface can shift dramatically. Higher volume typically narrows bid‑ask spreads, but only up to the point where market makers can replenish inventory without taking excessive risk. Beyond that threshold, spreads widen and price discovery becomes noisier....
Client research
Register free or login to read the full report
Registration is free. The full report includes chart snapshots, level work, technical tables, catalyst context, and the complete desk read.
Chat with XTRSK
Chat ready
Start a chat and the XTRSK team will be notified immediately.