
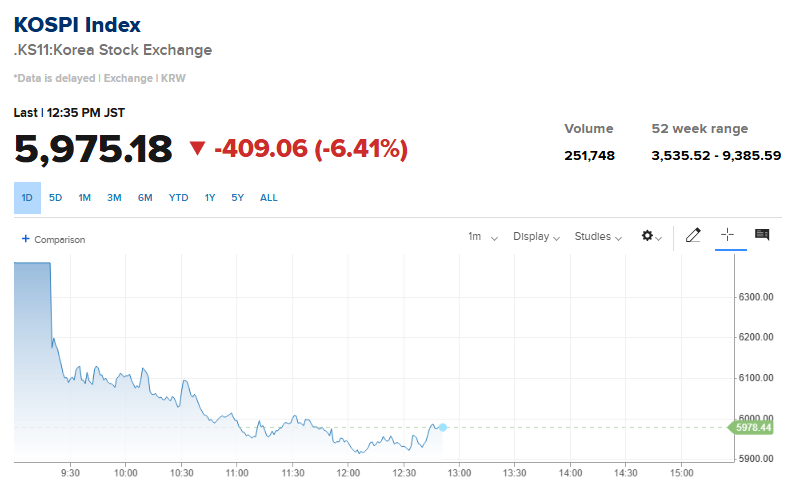
Understanding the 6.4% Korean Market Crash and Its Lessons for Quantitative Traders
Research preview
The South Korean equity market fell 6.4% in a single session, a move that shocked many participants and highlighted the importance of robust quantitative risk tools. This article dissects the dynamics of such a sharp drop, connects them to core concepts taught in advanced quantitative finance programs, and offers practical steps to strengthen a trading strategy against similar events. Why the Drop Was Larger Than Expected A 6.4% one‑day plunge is far beyond the typical daily volatility of the Korean market, which usually hovers around 1–2% on a standard deviation basis. When a move exceeds three standard deviations, it enters the realm of a tail event....
Client research
Register free or login to read the full report
Registration is free. The full report includes chart snapshots, level work, technical tables, catalyst context, and the complete desk read.
Chat with XTRSK
Chat ready
Start a chat and the XTRSK team will be notified immediately.