
XCore HFT / Trading Lab
XCore HFT Trading Lab: Production risk starts where the backtest ends
Quantitative execution, market-microstructure, and risk-control research from XTRSK.
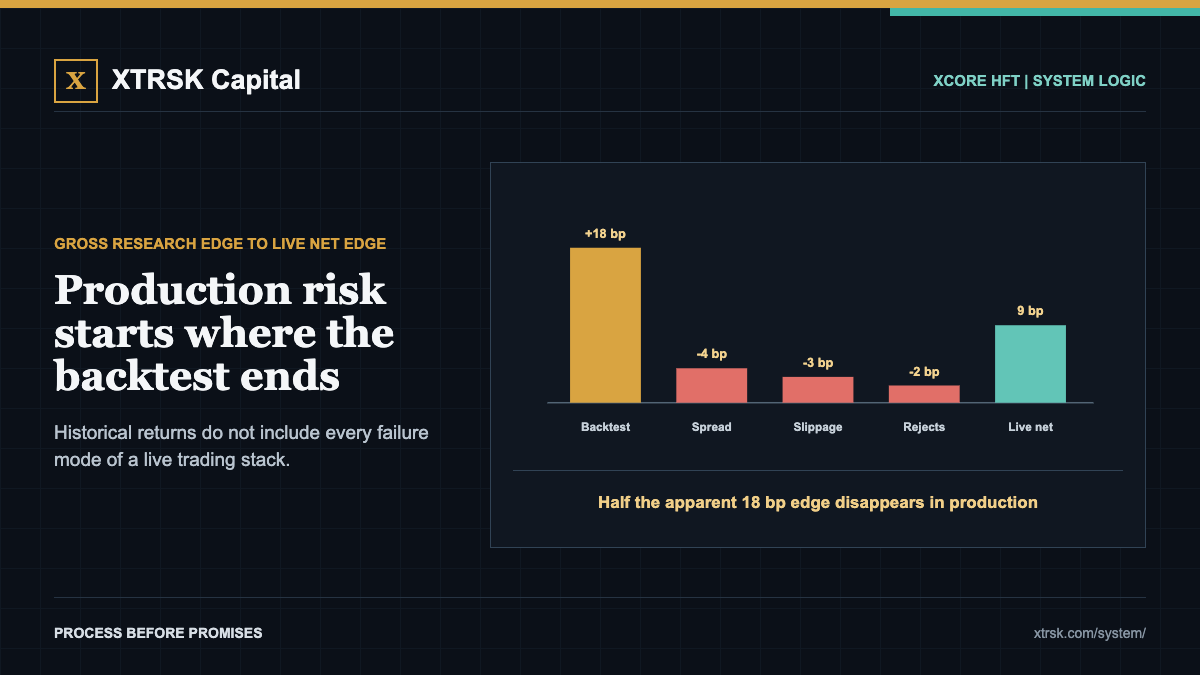
The hardest trading question is not whether an idea has edge. It is whether that edge remains executable at real size. Production risk starts where the backtest ends.
Good controls make hidden assumptions visible before capital discovers them. Historical returns do not include every failure mode of a live trading stack. Replay realistic message order and latency. Simulate rejects, partial fills, disconnects and stale data. Strip away the slogan and the operating words are live test, measurable, strategy and proof.
Put a boundary around the claim. A profitable signal can become untradeable when live acknowledgements arrive late and replacement orders overlap. The example is not a forecast or a promise; it shows which variable must be measured before the apparent opportunity can be treated as usable.
A compact operating checklist is: 1) include fees, spread, slippage and market impact; 2) shadow trade before increasing capital; 3) compare live feature distributions with research data. Add hard exposure ceilings, observable rejection reasons and an event trail that lets operations reconstruct the decision without guessing. Control sequence: 1 signal, 1 order path, 1 reconciled risk state.
The weak process asks whether the trade worked. The stronger process asks whether the decision was repeatable under the stated limits. Review the median, the stressed tail and the failure path separately. A result that survives only in quiet sessions, tiny size or perfect data is a research result, not yet a production capability.
The final check belongs at portfolio level, where correlation, financing, gross exposure and exit capacity can turn small positions into one concentrated bet. The objective is not to remove uncertainty. It is to size uncertainty, detect when assumptions break and preserve the ability to stop without creating a second problem.
Where is the largest gap between the risk your model reports and the risk your account can actually realise?
#Backtesting #AlgoTrading
The research behind this lesson
This paper explains Andrew Lo's lectures build risk analysis from return distributions and statistical measures, rather than treating one realised result as a complete description of risk.
Applied to this XCore lesson: For a fast strategy, median latency or average fill quality is not enough. The review has to include tail delays, stale-order frequency and the loss distribution when cancellation or routing behaves abnormally.
Explore XCore HFT: System details
PULSE XCORE HFT live account: Verify the live account on FX Blue
Live chat and updates: Telegram @xtrskhft
Source: Risk and Return
Educational content only. Trading leveraged products involves risk.
Chat with XTRSK
Chat ready
Start a chat and the XTRSK team will be notified immediately.