
XCore HFT / Trading Lab
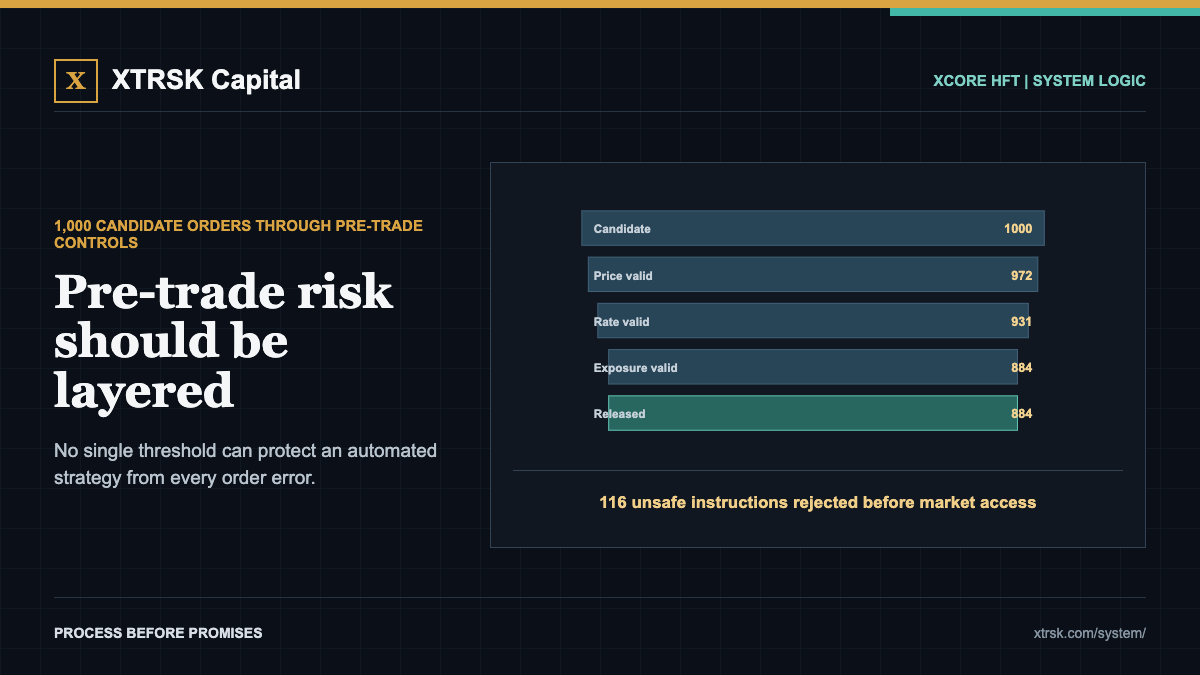
XCore HFT Trading Lab: Pre-trade risk should be layered
Quantitative execution, market-microstructure, and risk-control research from XTRSK.
A clean backtest can hide a messy execution problem. Live markets expose the difference immediately. Pre-trade risk should be layered.
The system becomes understandable only when data, decision, execution and capital are measured together. No single threshold can protect an automated strategy from every order error. Limit message frequency and repeated submissions. Cap strategy, instrument, account and firm-wide exposure. What matters operationally is the link between drawdown, proof, control and failure path.
Put a boundary around the claim. An order can pass a lot limit yet still be dangerous because correlated positions have already consumed the portfolio risk budget. The example is not a forecast or a promise; it shows which variable must be measured before the apparent opportunity can be treated as usable.
A compact operating checklist is: 1) reject stale signals and orders created from stale market data; 2) make every rejection observable to operations; 3) check maximum order quantity, notional value and price distance. Add hard exposure ceilings, observable rejection reasons and an event trail that lets operations reconstruct the decision without guessing. Control sequence: 1 signal, 1 order path, 1 reconciled risk state.
Averages make the system look orderly. Tail events reveal whether the controls were designed for live markets. Review the median, the stressed tail and the failure path separately. A result that survives only in quiet sessions, tiny size or perfect data is a research result, not yet a production capability.
Individual controls answer whether one instruction is permitted. Portfolio controls answer whether the firm can absorb all permitted instructions together. The objective is not to remove uncertainty. It is to size uncertainty, detect when assumptions break and preserve the ability to stop without creating a second problem.
Where is the largest gap between the risk your model reports and the risk your account can actually realise?
#RiskManagement #AlgoTrading
Research desk: from MIT theory to trading controls
This section is an original XTRSK synthesis of the cited teaching and research material. MIT is an educational source and does not endorse XTRSK, XCore HFT or PULSE.
High-Frequency Trading and Modern Market Microstructure
What the MIT material establishes: The seminar frames electronic markets as price-time-priority queues. It separates queue value into spread capture versus adverse-selection cost and the option value of retaining a place in line.
Applied to this XCore lesson: An order lifetime therefore cannot be based on elapsed time alone: the system must reassess whether its queue position, expected spread and adverse-selection risk still justify keeping the order alive.
Study the original MIT Operations Research Center seminar
Risk and Return
What the MIT material establishes: Andrew Lo's lectures build risk analysis from return distributions and statistical measures, rather than treating one realised result as a complete description of risk.
Applied to this XCore lesson: For a fast strategy, median latency or average fill quality is not enough. The review has to include tail delays, stale-order frequency and the loss distribution when cancellation or routing behaves abnormally.
Study the original MIT OpenCourseWare, Finance Theory I
Forward and Futures Contracts
What the MIT material establishes: This lecture develops forwards and futures around uncertain exchange rates while explicitly treating liquidity and counterparty risk as part of the contract problem.
Applied to this XCore lesson: In FX execution, a local cancel request is not the same as a cancelled exposure. Until the venue confirms the state, the risk engine must reserve capacity for a possible fill and prevent replacement orders from multiplying that exposure.
Study the original MIT OpenCourseWare, Finance Theory I
Further MIT learning path
- FX: Theories of Nominal Exchange Rates and Exchange-Rate Regimes
- Risk: Risk and Return
- HFT: High-Frequency Trading and Modern Market Microstructure
- Crypto: Blockchain and Money: Secondary Markets and Crypto-Exchanges
Explore XCore HFT: System details
PULSE XCORE HFT live account: Verify the live account on FX Blue
Live chat and updates: Telegram @xtrskhft
Educational content only. Trading leveraged products involves risk.
Chat with XTRSK
Chat ready
Start a chat and the XTRSK team will be notified immediately.