
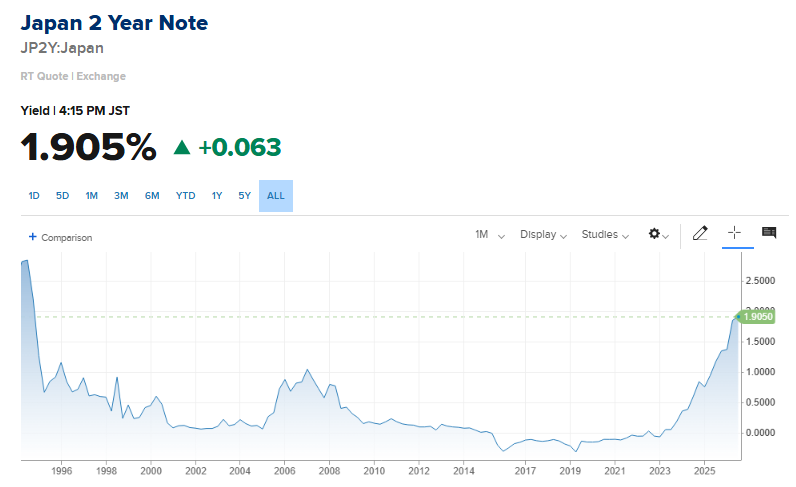
Japan’s 2‑Year Yield Breaks 1.9% – What It Means for Quant Strategies
Research preview
Japan’s 2‑year government bond yield has risen above 1.9% for the first time in more than three decades. The move reflects shifting expectations for monetary policy, inflation, and global risk sentiment. Quantitative traders can turn this macro shift into actionable signals by linking yield dynamics to cross‑asset relationships, term‑structure models, and risk‑adjusted positioning. Why the 2‑Year Yield Matters The 2‑year yield is a core short‑term benchmark in the Japanese bond market. When it climbs, it signals that market participants expect higher short‑run rates, either because the central bank may tighten or because inflation expectations are rising....
Client research
Register free or login to read the full report
Registration is free. The full report includes chart snapshots, level work, technical tables, catalyst context, and the complete desk read.
Chat with XTRSK
Chat ready
Start a chat and the XTRSK team will be notified immediately.