
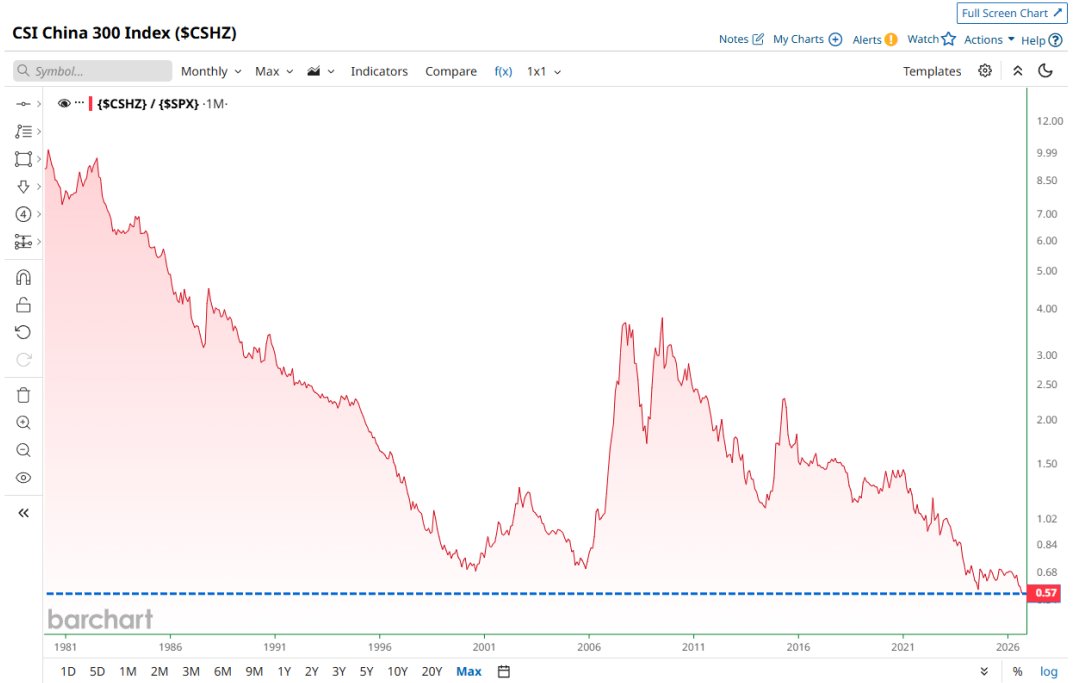
China’s Stock Underperformance vs the S&P 500: What Quant Traders Should Know
Research preview
Chinese equities have recently slipped far behind the S&P 500, creating the widest historical spread between the two markets. The divergence raises questions about risk, correlation, and portfolio construction for systematic strategies that trade across global equities. Why the Gap Matters for Quant Strategies The widening spread is more than a headline; it signals a shift in the risk‑return profile of Chinese assets relative to U.S. equities. When a market consistently underperforms a benchmark, its expected excess return shrinks, and the price of risk embedded in factor models must be re‑estimated....
Client research
Register free or login to read the full report
Registration is free. The full report includes chart snapshots, level work, technical tables, catalyst context, and the complete desk read.
Chat with XTRSK
Chat ready
Start a chat and the XTRSK team will be notified immediately.