
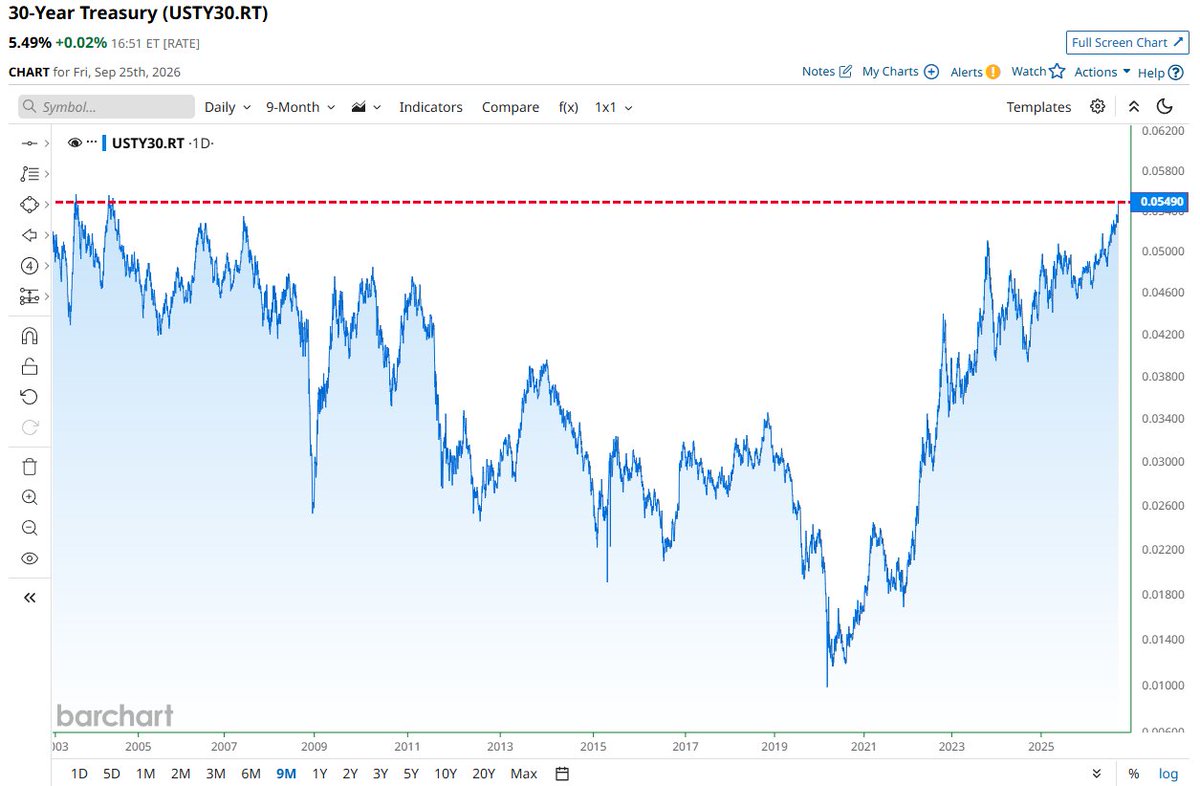
How the 30‑Year Treasury Yield’s 22‑Year High Reshapes Quantitative Strategies
Research preview
The 30‑year U.S. Treasury yield closed at 5.49%, a level not seen in more than two decades. This unprecedented move has immediate consequences for fixed‑income models, risk premia, and portfolio construction. The following analysis explains the mechanics behind the surge, connects it to core quantitative concepts, and outlines actionable steps for systematic traders. Yield Shock and the Term Structure A sudden rise in the longest‑dated Treasury rate compresses the yield curve, especially when shorter maturities remain near historic lows. The flattening reflects higher expectations for long‑run inflation and tighter monetary policy....
Client research
Register free or login to read the full report
Registration is free. The full report includes chart snapshots, level work, technical tables, catalyst context, and the complete desk read.
Chat with XTRSK
Chat ready
Start a chat and the XTRSK team will be notified immediately.