
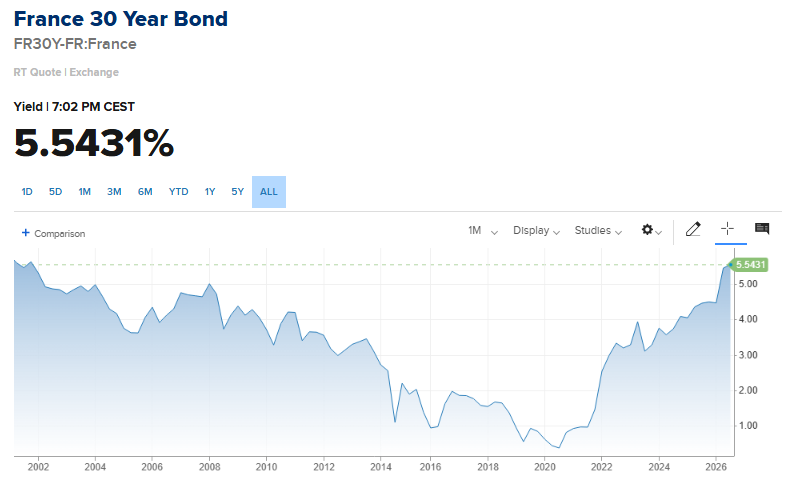
France’s 30‑Year Bond Yield Peaks – Implications for Quantitative Traders
Research preview
The French 30‑year government bond yield has surged to a level not seen in more than two decades, signaling a shift in the euro‑area fixed‑income landscape. This article dissects the drivers behind the move, connects the event to core quantitative finance concepts, and outlines actionable steps for systematic traders. Market backdrop and yield dynamics The recent breakout in the long‑term French sovereign yield reflects a confluence of macro‑economic and policy factors. Inflation expectations have risen sharply across the euro zone, prompting central‑bank officials to signal a more aggressive tightening path. At the same time, fiscal concerns related to debt sustainability have heightened risk premia on long‑dated government paper....
Client research
Register free or login to read the full report
Registration is free. The full report includes chart snapshots, level work, technical tables, catalyst context, and the complete desk read.
Chat with XTRSK
Chat ready
Start a chat and the XTRSK team will be notified immediately.