
How Upcoming Rate Hikes Reshape Quantitative Risk Management Strategies
Research preview
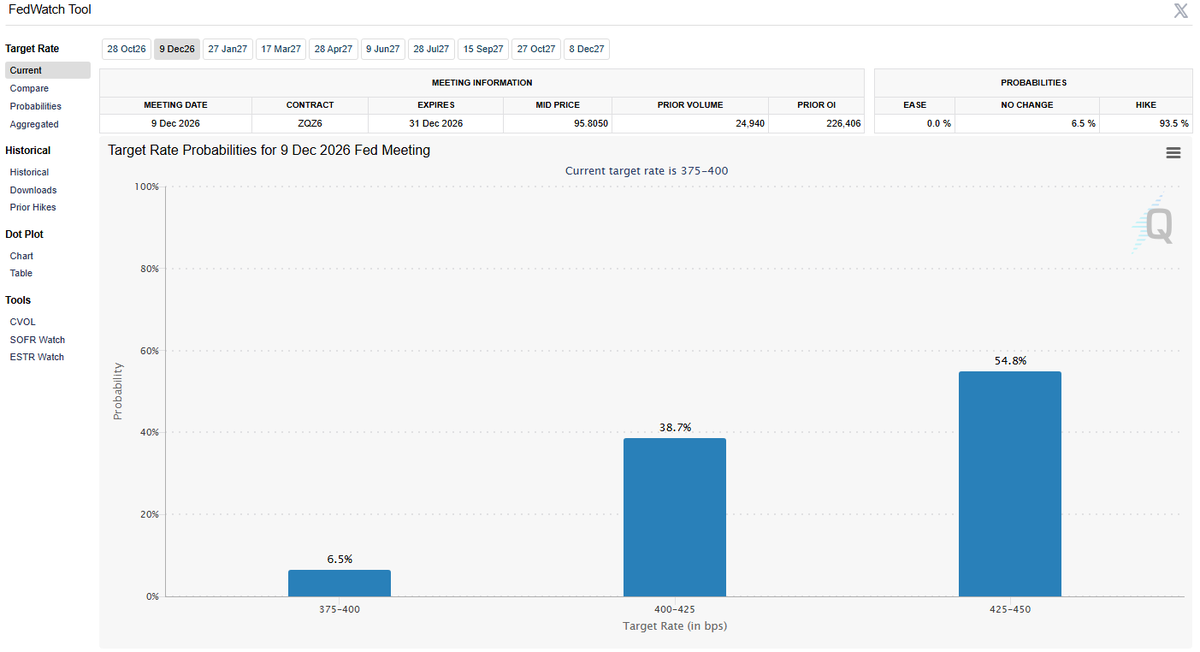
The market now assigns a 55 % probability to two Federal Reserve rate hikes before year‑end. This shift in monetary policy expectations forces quantitative traders to revisit their risk models, capital allocation, and stress‑testing frameworks. The following article connects the event to core concepts from a quantitative risk management curriculum and provides actionable steps for practitioners. Rethinking Loss Distributions Under Rate‑Shift Scenarios A change in interest rates alters the distribution of asset returns, especially for fixed‑income and rate‑sensitive equities. Historically, rate hikes increase volatility and introduce skewness as bond prices fall and equity sectors react unevenly....
Client research
Register free or login to read the full report
Registration is free. The full report includes chart snapshots, level work, technical tables, catalyst context, and the complete desk read.
Chat with XTRSK
Chat ready
Start a chat and the XTRSK team will be notified immediately.