
XCore HFT / Trading Lab
XCore HFT Trading Lab: Speed is an end-to-end latency budget
Quantitative execution, market-microstructure, and risk-control research from XTRSK.
Most automated-trading failures begin as small mismatches: stale data, incomplete fills, delayed controls or misunderstood exposure. Speed is an end-to-end latency budget.
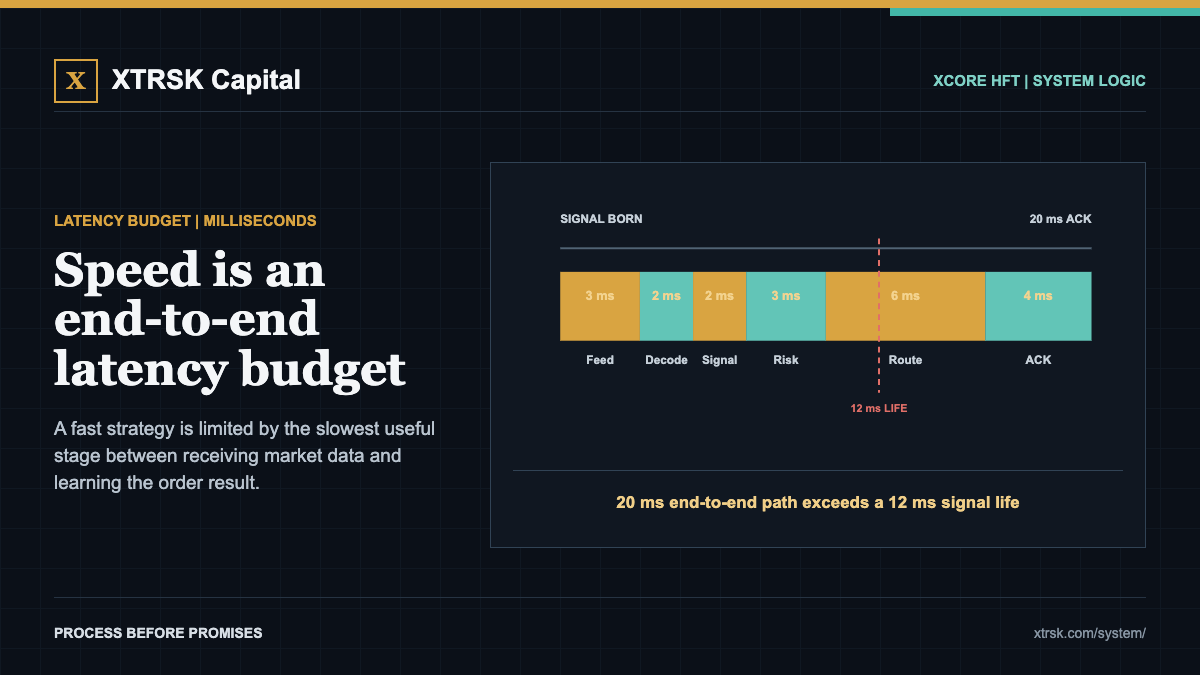
A robust desk turns the idea into a sequence that can be measured and interrupted. A fast strategy is limited by the slowest useful stage between receiving market data and learning the order result. Separate feed transit, decoding, signal calculation, risk checks, routing and acknowledgement time. Measure median, tail latency and jitter rather than advertising one best-case number. The useful vocabulary is concrete—live test, decision, edge and engineering—because each term maps to a control.
Put a boundary around the claim. A two-millisecond signal calculation has little value if the complete order path consumes twenty milliseconds and the opportunity normally disappears in twelve. The example is not a forecast or a promise; it shows which variable must be measured before the apparent opportunity can be treated as usable.
A compact operating checklist is: 1) compare signal half-life with the complete decision-to-acknowledgement path; 2) treat clock synchronisation and timestamp quality as part of the measurement system; 3) separate feed transit, decoding, signal calculation, risk checks, routing and acknowledgement time. Add hard exposure ceilings, observable rejection reasons and an event trail that lets operations reconstruct the decision without guessing. Control sequence: 1 signal, 1 order path, 1 reconciled risk state.
It is easy to confuse activity with edge and a fill with good execution. Review the median, the stressed tail and the failure path separately. A result that survives only in quiet sessions, tiny size or perfect data is a research result, not yet a production capability.
The account experiences combined profit, loss and liquidity demand, even when models are monitored in separate dashboards. The objective is not to remove uncertainty. It is to size uncertainty, detect when assumptions break and preserve the ability to stop without creating a second problem.
Which tail metric has taught you more than the corresponding average?
#HFT #LowLatency
Research desk: from MIT theory to trading controls
This section is an original XTRSK synthesis of the cited teaching and research material. MIT is an educational source and does not endorse XTRSK, XCore HFT or PULSE.
High-Frequency Trading and Modern Market Microstructure
What the MIT material establishes: The seminar frames electronic markets as price-time-priority queues. It separates queue value into spread capture versus adverse-selection cost and the option value of retaining a place in line.
Applied to this XCore lesson: An order lifetime therefore cannot be based on elapsed time alone: the system must reassess whether its queue position, expected spread and adverse-selection risk still justify keeping the order alive.
Study the original MIT Operations Research Center seminar
Risk and Return
What the MIT material establishes: Andrew Lo's lectures build risk analysis from return distributions and statistical measures, rather than treating one realised result as a complete description of risk.
Applied to this XCore lesson: For a fast strategy, median latency or average fill quality is not enough. The review has to include tail delays, stale-order frequency and the loss distribution when cancellation or routing behaves abnormally.
Study the original MIT OpenCourseWare, Finance Theory I
Forward and Futures Contracts
What the MIT material establishes: This lecture develops forwards and futures around uncertain exchange rates while explicitly treating liquidity and counterparty risk as part of the contract problem.
Applied to this XCore lesson: In FX execution, a local cancel request is not the same as a cancelled exposure. Until the venue confirms the state, the risk engine must reserve capacity for a possible fill and prevent replacement orders from multiplying that exposure.
Study the original MIT OpenCourseWare, Finance Theory I
Further MIT learning path
- FX: Theories of Nominal Exchange Rates and Exchange-Rate Regimes
- Risk: Risk and Return
- HFT: High-Frequency Trading and Modern Market Microstructure
- Crypto: Blockchain and Money: Secondary Markets and Crypto-Exchanges
Explore XCore HFT: System details
PULSE XCORE HFT live account: Verify the live account on FX Blue
Live chat and updates: Telegram @xtrskhft
Educational content only. Trading leveraged products involves risk.
Chat with XTRSK
Chat ready
Start a chat and the XTRSK team will be notified immediately.