
How Schwab’s Earnings Reveal Portfolio Volatility Lessons for Quant Traders
Research preview
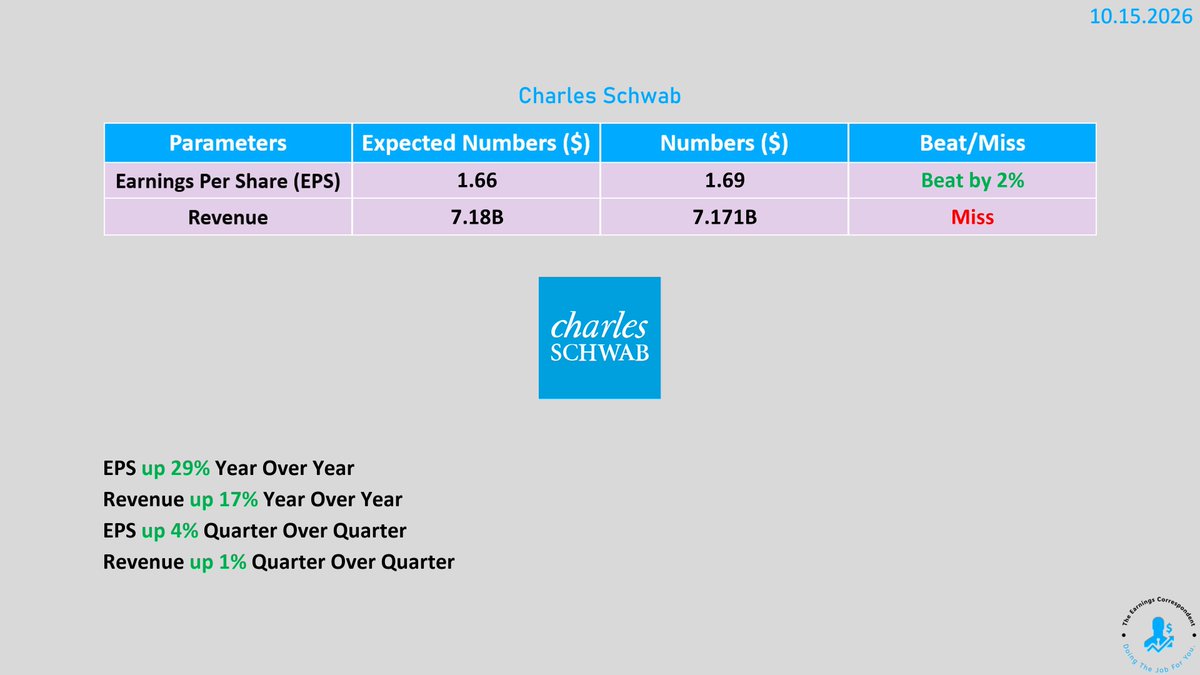
Schwab’s latest earnings release sparked a sharp move in its stock, offering a timely case study for quantitative traders. By dissecting the price reaction through the lens of modern finance theory, we can reinforce core concepts such as correlation, diversification, and risk‑adjusted return that underpin algorithmic strategies. The Earnings Shock and Immediate Market Response When a large broker‑dealer posts results that differ from consensus, the market often reacts quickly. Schwab’s earnings beat (or miss) caused a single‑day price swing of roughly 4 percent, well beyond its typical daily volatility....
Client research
Register free or login to read the full report
Registration is free. The full report includes chart snapshots, level work, technical tables, catalyst context, and the complete desk read.
Chat with XTRSK
Chat ready
Start a chat and the XTRSK team will be notified immediately.