
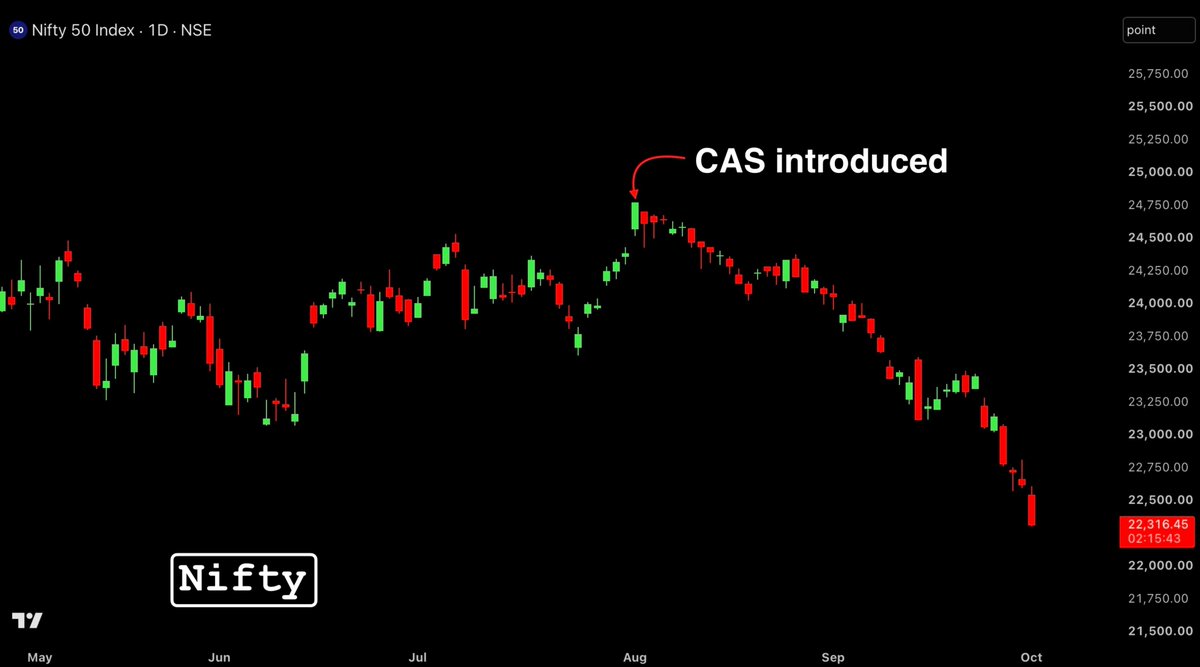
Why NIFTY50’s 10% Decline Highlights the Power of Correlation in Portfolio Risk
Research preview
The NIFTY50 index has slid 10% since the introduction of the new CAS framework, a move that has sparked debate about market efficiency and risk management. Understanding how asset correlations drive portfolio volatility can help quantitative traders turn such market shifts into strategic opportunities. The Role of Correlation in Portfolio Volatility When two assets move independently, the combined risk of a portfolio is lower than the sum of individual risks. This effect is captured by the correlation coefficient, which ranges from –1 (perfect negative correlation) to +1 (perfect positive correlation). A zero‑correlation pair reduces overall volatility because the assets’ price swings tend to offset each other....
Client research
Register free or login to read the full report
Registration is free. The full report includes chart snapshots, level work, technical tables, catalyst context, and the complete desk read.
Chat with XTRSK
Chat ready
Start a chat and the XTRSK team will be notified immediately.