
How Albanian Protest Volatility Informs Quantitative Trading Risk Models
Research preview
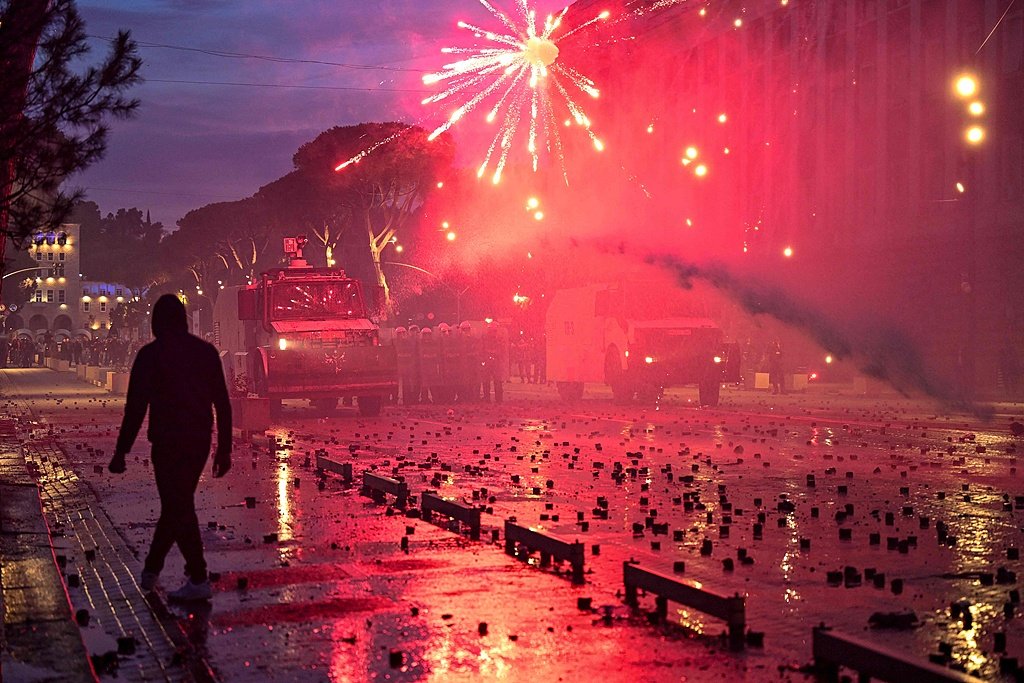
The streets of Tirana have been a laboratory of market‑like dynamics since the protests erupted on October 13. For quantitative traders, the rapid escalation from peaceful gatherings to violent clashes offers a real‑time case study of how exogenous political risk can shock asset prices, liquidity, and volatility. This article translates the Albanian unrest into actionable insights for building and stress‑testing statistical arbitrage and factor models, while also highlighting relevant academic concepts from advanced finance programs. Political Shocks as Stochastic Events Political unrest behaves like a stochastic jump process: the probability of a shock is low in calm periods, then spikes dramatically when grievances reach a tipping point....
Client research
Register free or login to read the full report
Registration is free. The full report includes chart snapshots, level work, technical tables, catalyst context, and the complete desk read.
Chat with XTRSK
Chat ready
Start a chat and the XTRSK team will be notified immediately.