
XCore HFT / Trading Lab
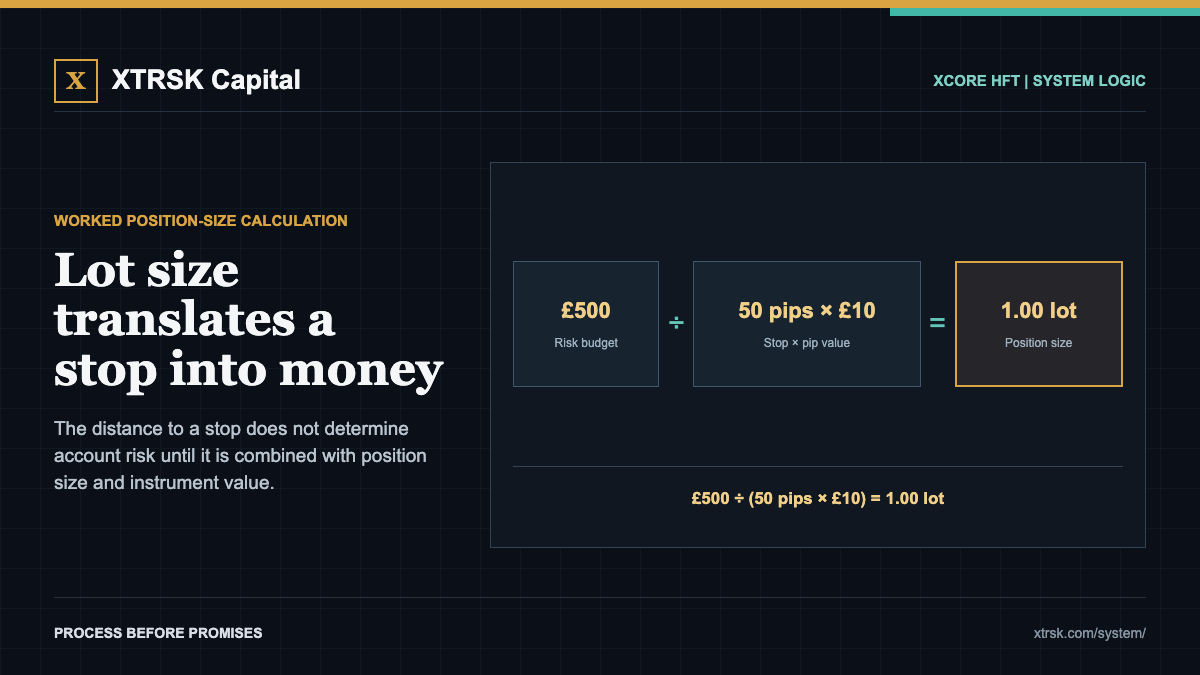
XCore HFT Trading Lab: Lot size translates a stop into money
Quantitative execution, market-microstructure, and risk-control research from XTRSK.
Risk in systematic trading is rarely one number. It is a chain of assumptions that must remain true at the same time. Lot size translates a stop into money.
A compact operating checklist is: 1) start with an account risk budget; 2) convert price distance through contract size, tick value and currency; 3) round down to the venue lot increment.
Which measurement would most quickly reveal that this control is failing in your live order path?
#PositionSizing #RiskManagement
Research desk: from MIT theory to trading controls
This section is an original XTRSK synthesis of the cited teaching and research material. MIT is an educational source and does not endorse XTRSK, XCore HFT or PULSE.
Risk and Return
What the MIT material establishes: Andrew Lo's lectures build risk analysis from return distributions and statistical measures, rather than treating one realised result as a complete description of risk.
Applied to this XCore lesson: For a fast strategy, median latency or average fill quality is not enough. The review has to include tail delays, stale-order frequency and the loss distribution when cancellation or routing behaves abnormally.
Study the original MIT OpenCourseWare, Finance Theory I
Forward and Futures Contracts
What the MIT material establishes: This lecture develops forwards and futures around uncertain exchange rates while explicitly treating liquidity and counterparty risk as part of the contract problem.
Applied to this XCore lesson: In FX execution, a local cancel request is not the same as a cancelled exposure. Until the venue confirms the state, the risk engine must reserve capacity for a possible fill and prevent replacement orders from multiplying that exposure.
Study the original MIT OpenCourseWare, Finance Theory I
Theories of Nominal Exchange Rates and Exchange-Rate Regimes
What the MIT material establishes: The course separates short- and long-run exchange-rate mechanisms and then examines currency crises, exchange-rate regimes and capital controls.
Applied to this XCore lesson: A systematic FX process should distinguish execution controls from macro regime assumptions. A low-latency order rule cannot repair a model whose exchange-rate premise no longer fits the policy regime.
Study the original MIT OpenCourseWare, Applied Macro and International Economics
Further MIT learning path
- FX: Theories of Nominal Exchange Rates and Exchange-Rate Regimes
- Risk: Risk and Return
- HFT: High-Frequency Trading and Modern Market Microstructure
- Crypto: Blockchain and Money: Secondary Markets and Crypto-Exchanges
Explore XCore HFT: System details
PULSE XCORE HFT live account: Verify the live account on FX Blue
Live chat and updates: Telegram @xtrskhft
Educational content only. Trading leveraged products involves risk.
Chat with XTRSK
Chat ready
Start a chat and the XTRSK team will be notified immediately.