XCore HFT / Trading Lab
PULSE: Order type is a risk decision
Quantitative execution, market-microstructure, and risk-control research from XTRSK.
What this problem really is
There is a version of this problem that looks tidy in a slide and behaves very differently once orders reach a live venue. Market, limit, immediate-or-cancel and fill-or-kill instructions trade completion certainty against price and information leakage.
Order type is a risk decision. is easy to describe and harder to operate, and the gap between the description and the operation is where trading risk accumulates. A defensible design names every dependency, every timeout and every assumption that must hold for the result to remain valid.
A useful test is to ask which single record, if it were lost, would make the result impossible to explain; that record is the one to protect first.
The mechanism should degrade predictably: when a dependency slows or disappears, the system should narrow its behaviour rather than invent a new one.
The mechanism is a sequence, not a single decision. Each stage consumes the output of the previous one, and a small error early in the chain is amplified by everything that follows.
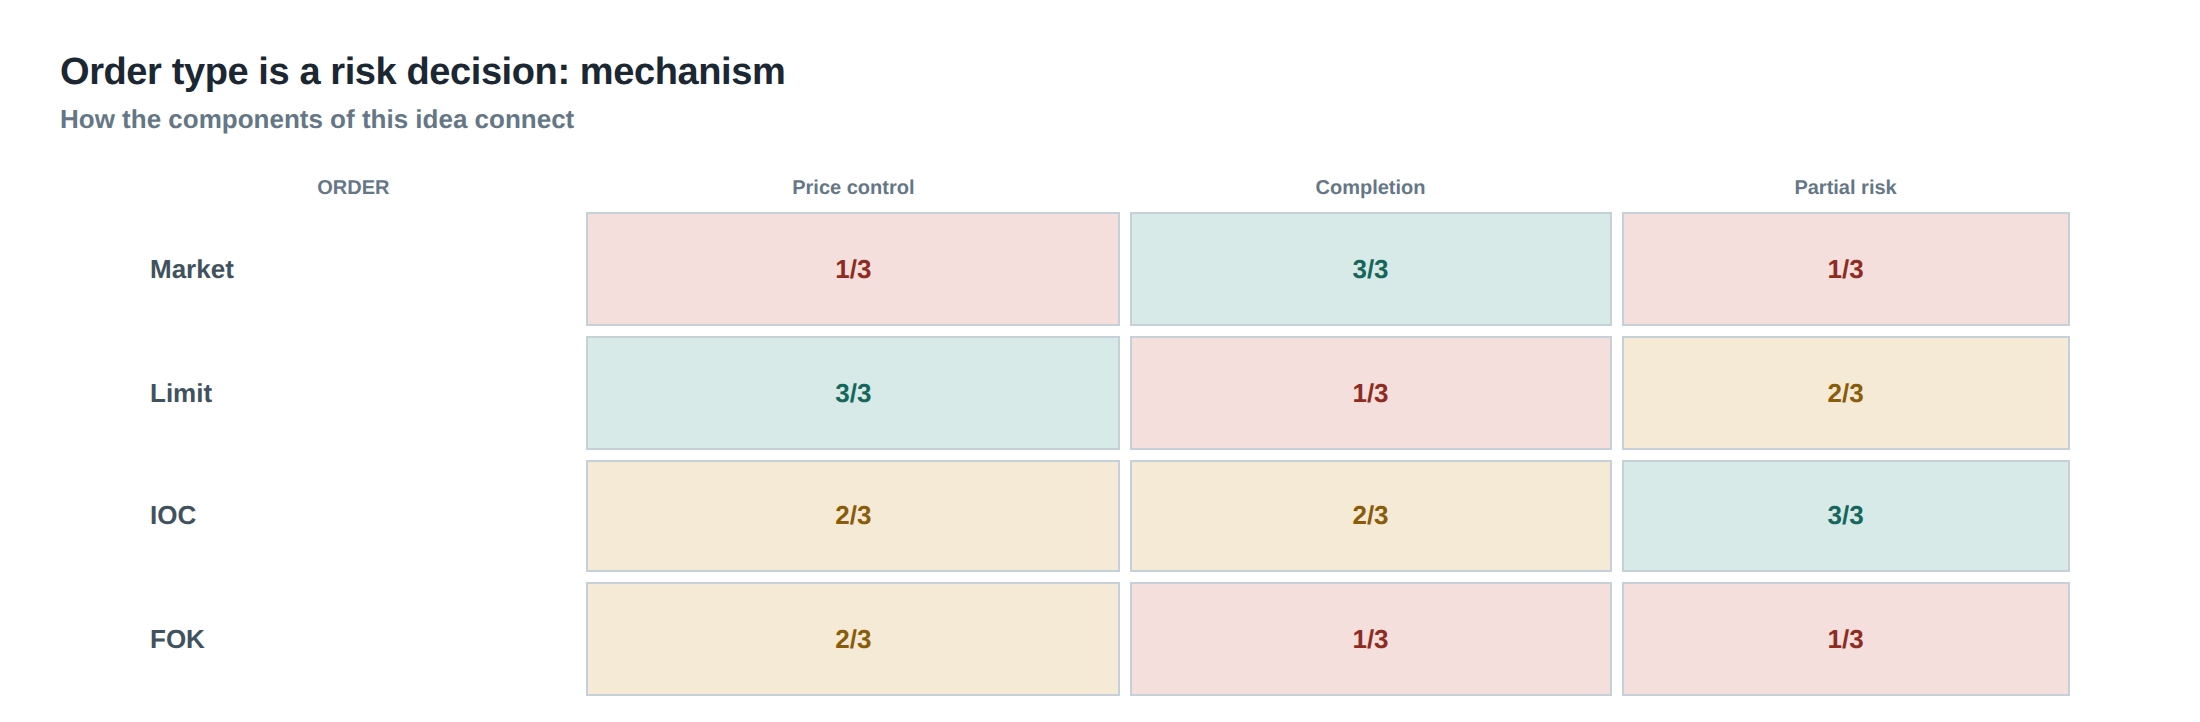
How the mechanism works, step by step
1) Select the instruction from signal urgency and available depth. 2) Define acceptable partial-fill behaviour. 3) Measure reject and cancel outcomes. 4) Include the cost of missed trades. 5) Avoid one default order type for every regime.
A defensible design names every dependency, every timeout and every assumption that must hold for the result to remain valid.
When the desk cannot explain the mechanism in one page of plain language, the model is usually hiding an assumption rather than simplifying one.
The mechanism is only as reliable as its least observable stage, so measurement effort should follow the weakest link rather than the most interesting one.
The fifth is the recovery path. A desk that can stop but cannot restart safely has only solved half of the problem it set out to solve.
A worked example with real numbers
A fill-or-kill order can prevent residual quantity, but it may reject an opportunity that an immediate-or-cancel instruction would partially complete.
Keep the units explicit: currency, notional, size and time. Most apparent edge disappears in a unit conversion that nobody checked.
Recompute the example under a stress variant — wider spreads, thinner depth and slower acknowledgements — and see how much of the margin remains.
The point of the example is to locate the break-even assumption. The strategy is a bet that this assumption holds more often than the cost of being wrong.
Write the result as a range rather than a point estimate, so the reader can see which variable dominates the outcome.
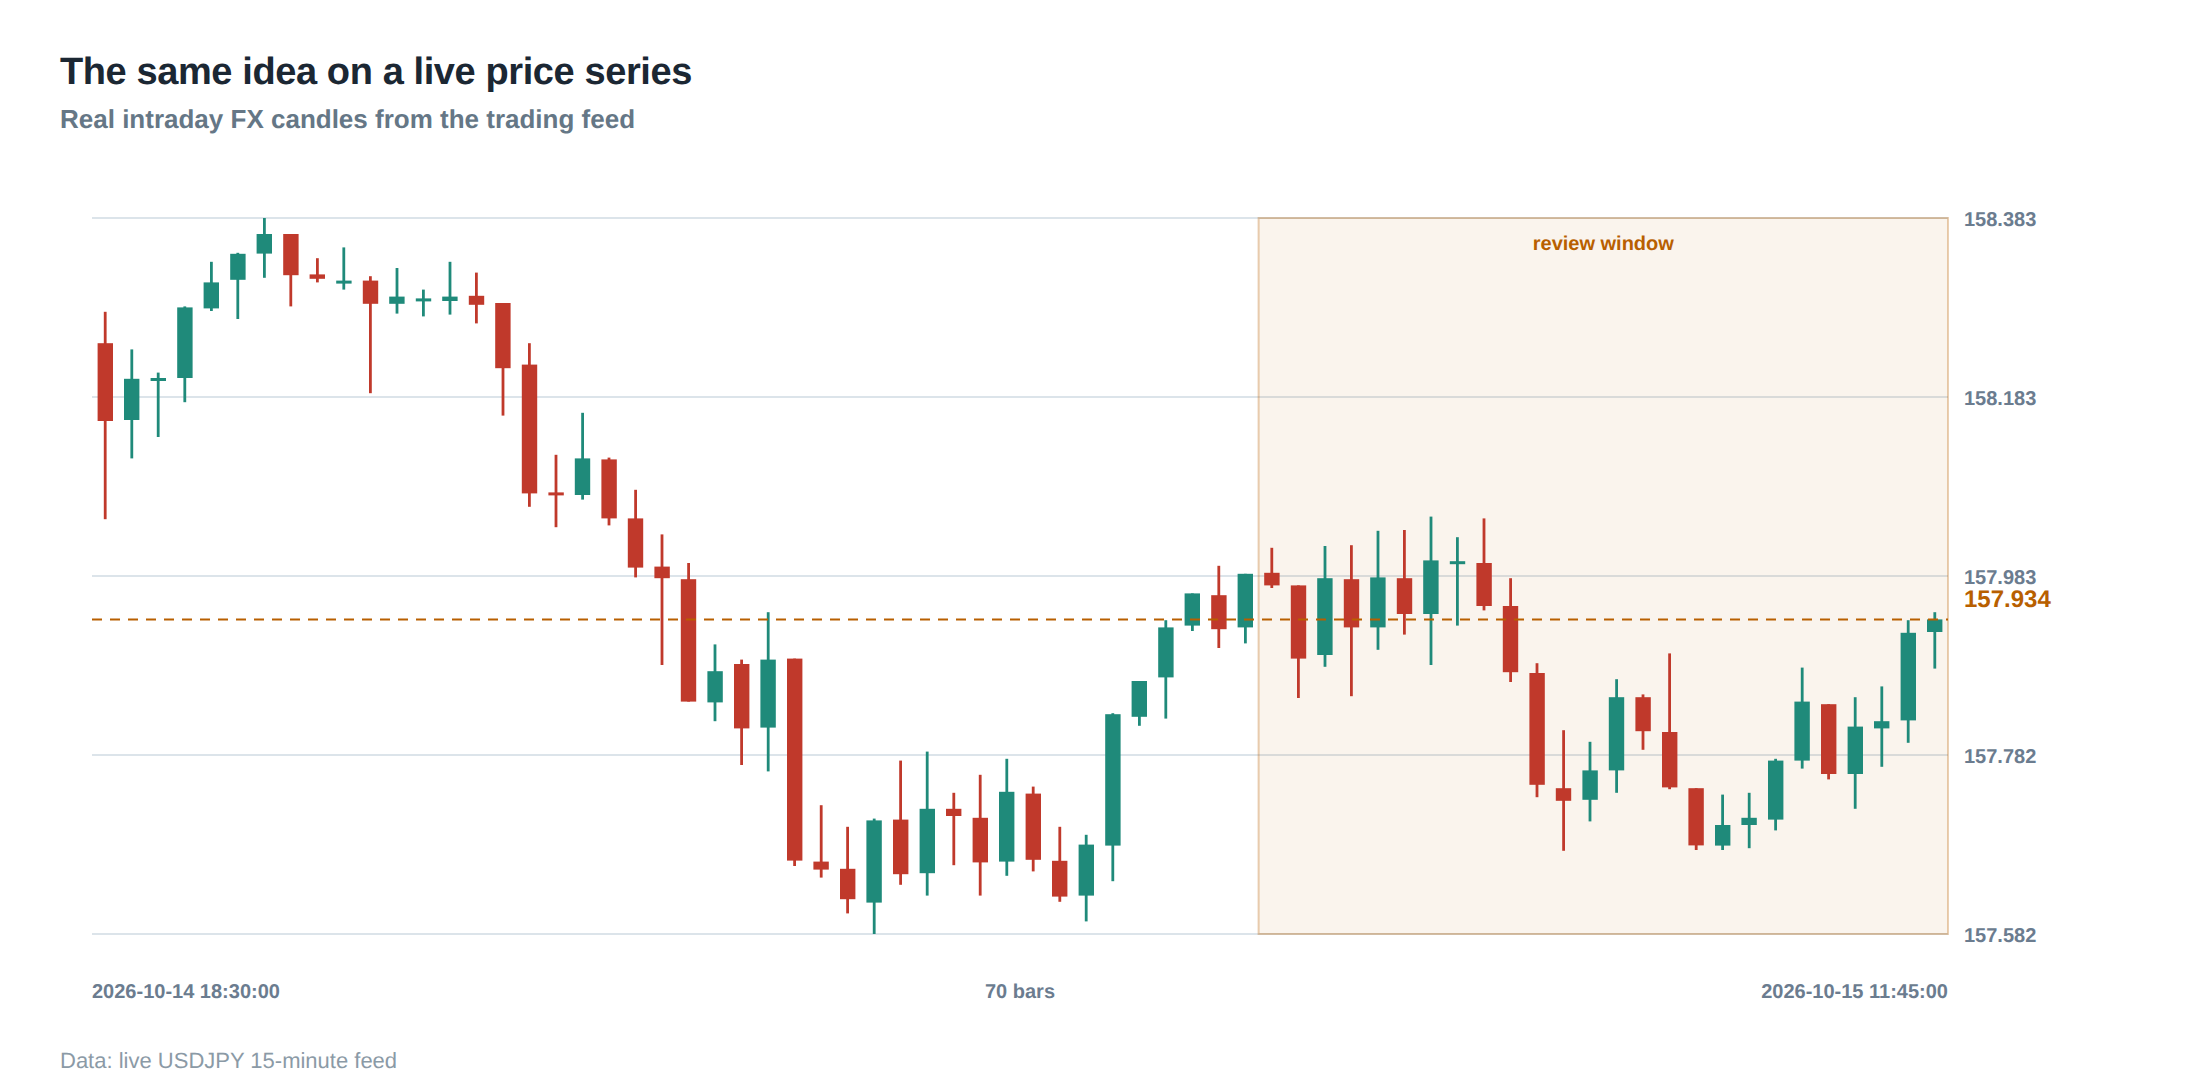
Where it breaks in live markets
The fifth is the recovery path. A desk that can stop but cannot restart safely has only solved half of the problem it set out to solve.
The first failure mode is silent drift: the measurement that justified the strategy stops matching the conditions that produce it, and nobody is watching the difference between the two.
The second is a control that exists in configuration but not in behaviour. A limit that reads stale or unreconciled state is documentation, not protection.
The third is concentration. Several positions that look independent share a factor, a venue or a liquidity source, and the book quietly becomes one larger bet than the dashboard suggests.
The fourth is capacity. The same signal that earns a thin edge at small size consumes that edge through market impact as the order grows.
The operating path, stage by stage
A compact checklist is: 1) measure reject and cancel outcomes; 2) include the cost of missed trades; 3) avoid one default order type for every regime.
A rehearsed recovery is part of the operating path, not an afterthought once the incident has already started.
Give each stage an owner and a reason code so that a post-mortem can reconstruct the path without relying on memory.
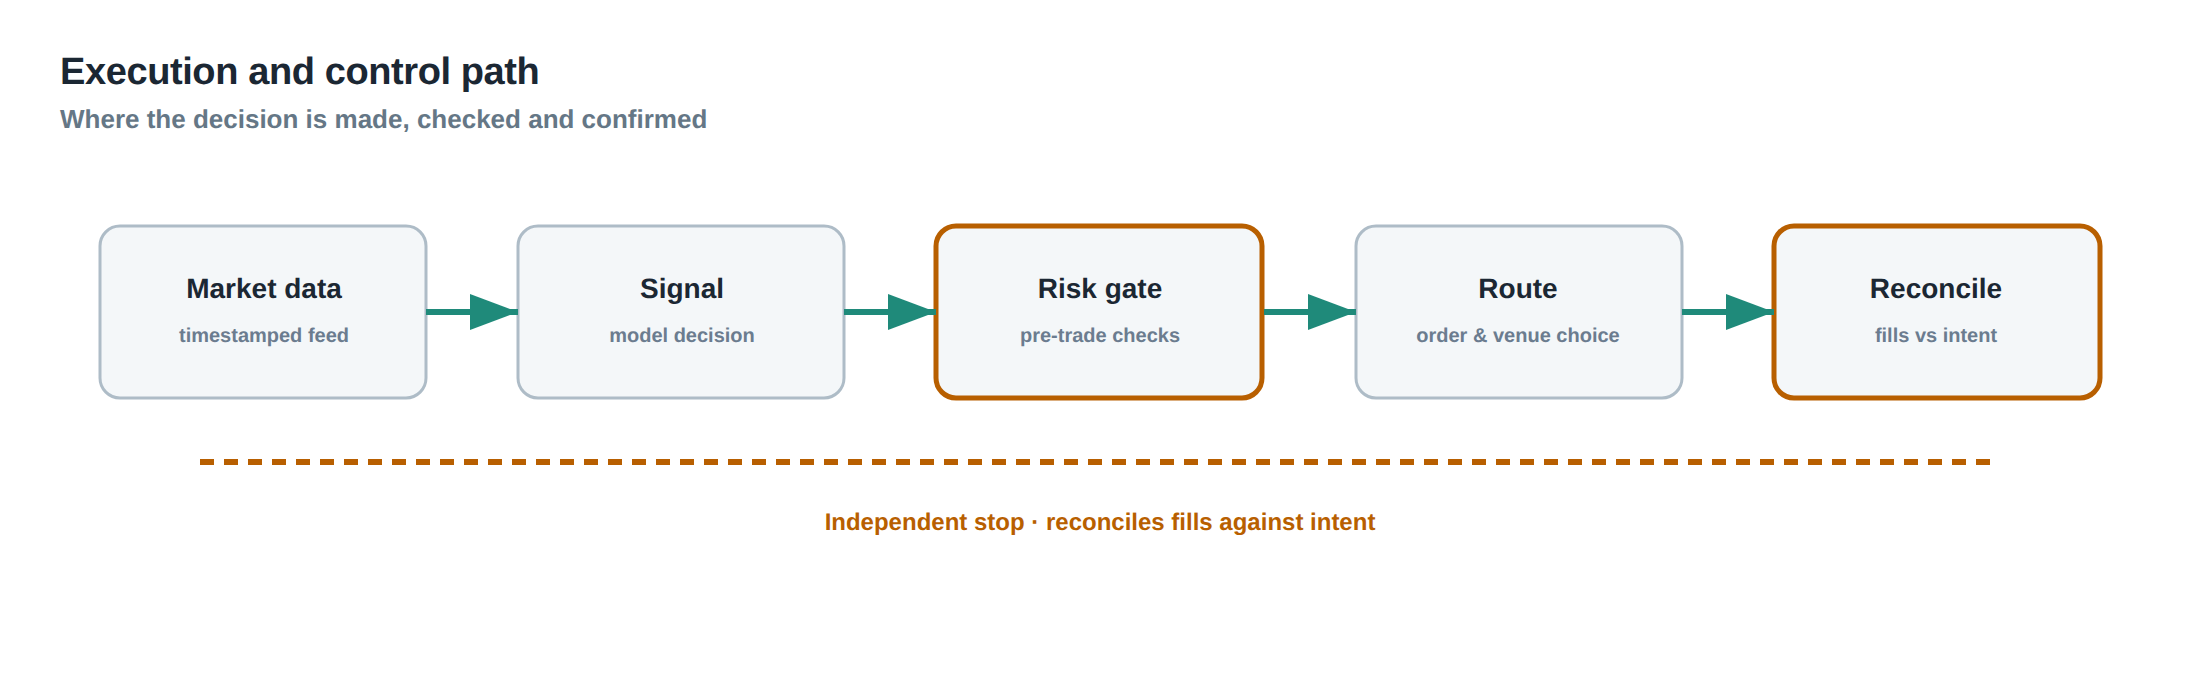
The path should be short enough to reason about and instrumented enough to prove. Every extra hop is another place for state to diverge.
Reconciliation closes the loop: the system compares intended exposure with confirmed exposure and refuses to continue on an unexplained gap.
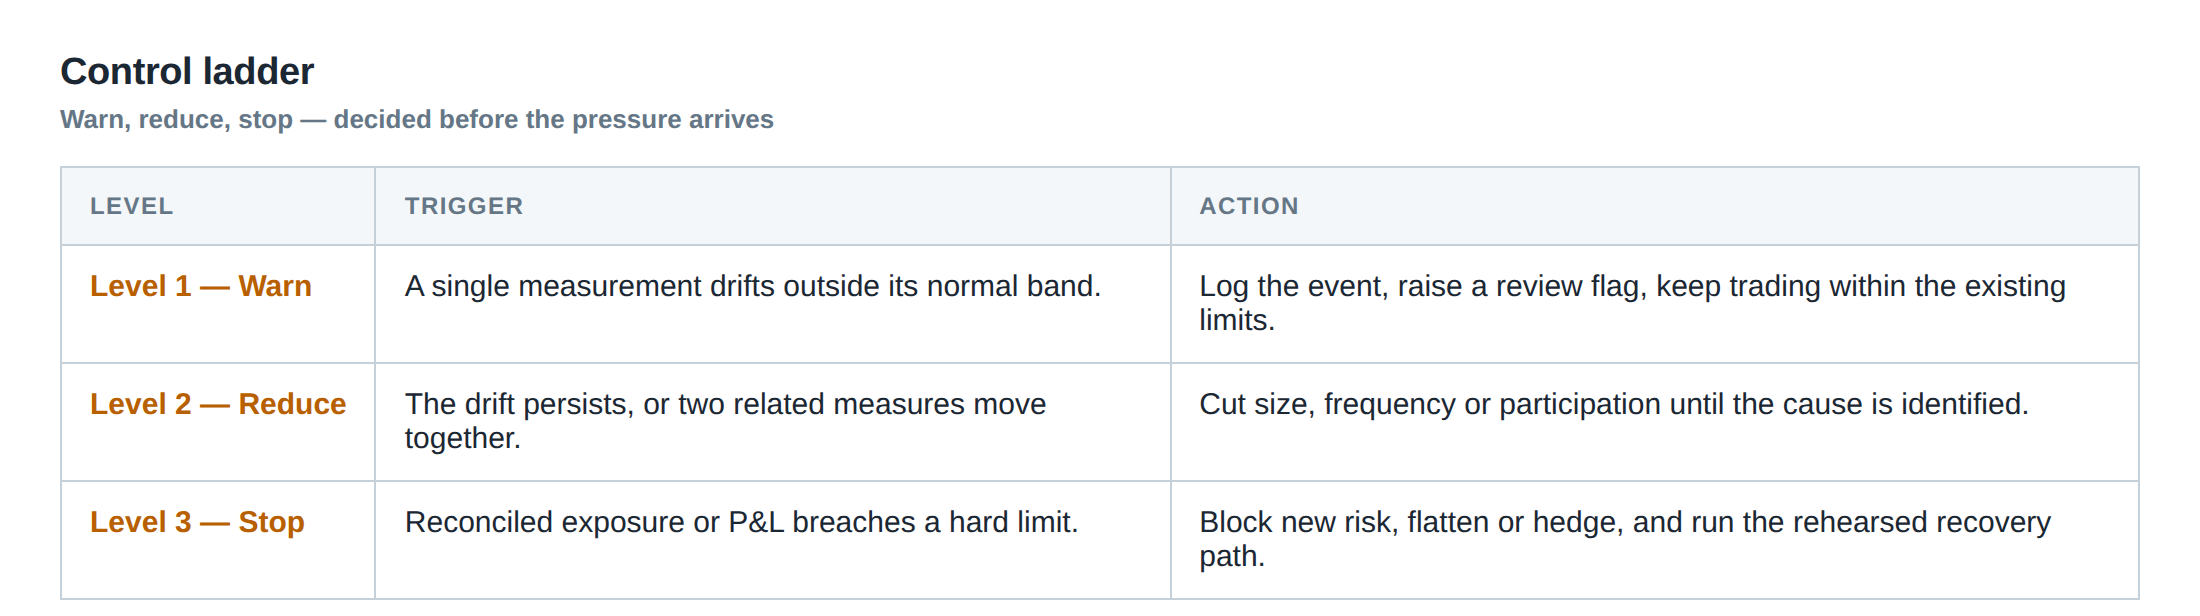
Controls that act before the damage
Use a three-level ladder. Level one warns and records; level two reduces size, frequency or participation; level three blocks new risk and invokes the rehearsed recovery path.
Prefer several narrow, well-understood limits over one clever aggregate that nobody can explain under pressure.
A control that fires constantly is a design fault, while a control that never fires has not really been tested.
The sequence matters: warn, then reduce, then stop, with each step leaving a record that the next one can trust.
Hard limits belong in a layer the strategy cannot edit at runtime, so a bug or a careless configuration change cannot lift its own ceiling.
How to measure whether it is working
Choose a denominator and keep it fixed. Changing the base between reports makes progress impossible to judge.
Separate leading indicators that move first from lagging outcomes that confirm later; the leading ones buy time to act.
Compare live behaviour with the backtest under the same regime, not against the best historical period.
Set the review cadence before the pressure arrives, so the response becomes a decision rather than a reaction.
Measure the median and the tail separately. An acceptable average can conceal a loss distribution the account could not survive twice.
Turning the idea into a daily routine
Start each session by confirming that the data, the clock and the venue state agree. Most model failures are really synchronisation failures discovered late.
Review the previous session against the same three questions: what was expected, what happened, and what was the largest unexplained gap.
Keep a short list of conditions that would make the desk stand down. A pre-committed exit is worth more than a clever entry.
Feed the review back into the limits. A control that never changes after new evidence is not learning from the market.
The portfolio view
Risk should aggregate across instruments and strategies before another order is allowed to consume scarce liquidity or margin.
Aggregate by risk factor rather than by strategy label, because two desks can easily be one position.
Ask what happens to the whole book if the shared dependency fails at the worst moment, then size for that day rather than for the average one.
Then widen the lens. A permitted order can still be the wrong portfolio action when several strategies compete for the same capital, venue capacity or hedge.
Where does your desk draw the line between normal execution variation and a risk event that demands action?
About the research behind this lesson
The seminar frames electronic markets as price-time-priority queues. It separates queue value into spread capture versus adverse-selection cost and the option value of retaining a place in line.
Applied to this lesson: An order lifetime therefore cannot be based on elapsed time alone: the system must reassess whether its queue position, expected spread and adverse-selection risk still justify keeping the order alive.
Explore PULSE: System details
PULSE live account: Verify the live account on FX Blue
Live chat and updates: Telegram @xtrskhft
Source: High-Frequency Trading and Modern Market Microstructure
Educational content only. Trading leveraged products involves risk.
Chat with XTRSK
Chat ready
Start a chat and the XTRSK team will be notified immediately.