
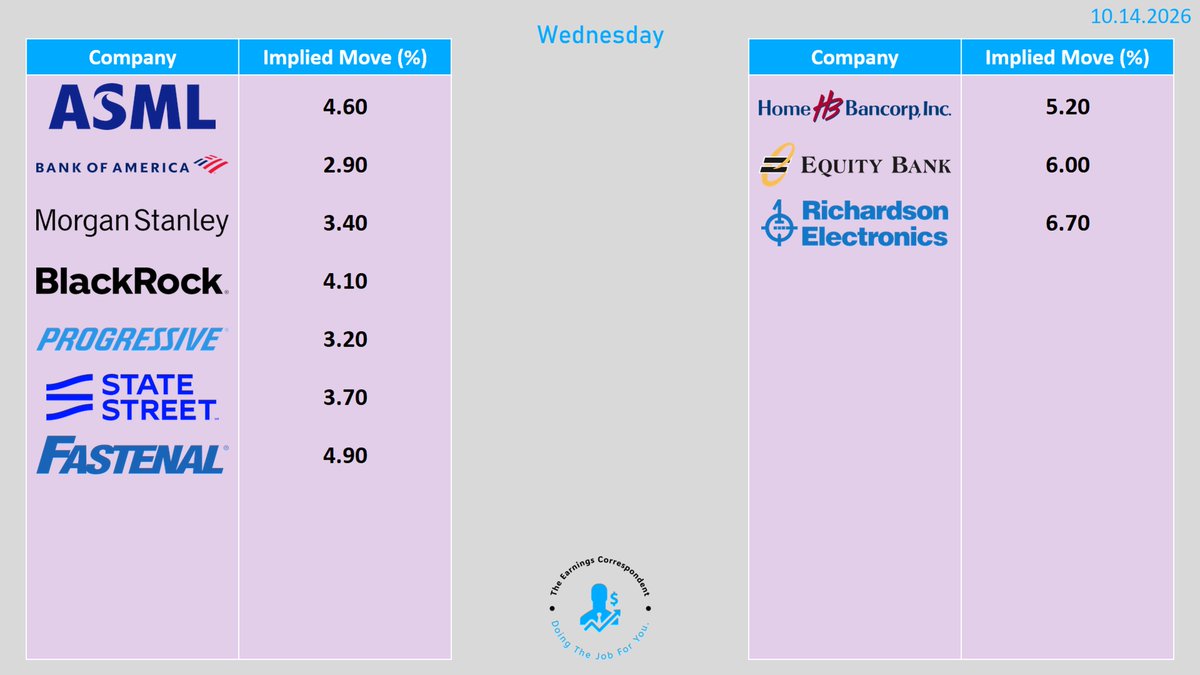
Translating Implied Move Data into Quantitative Trading Strategies
Research preview
The earnings calendar often brings a burst of volatility that can be quantified through implied move calculations. By converting these market‑derived expectations into actionable metrics, systematic traders can better position their portfolios around earnings releases. This article walks through the mechanics of implied moves, illustrates how to integrate them with risk‑adjusted performance measures, and outlines practical steps for building a robust earnings‑driven strategy. Understanding Implied Moves Implied move figures represent the market’s consensus forecast of how far a stock’s price might swing around an upcoming earnings announcement. They are derived from the price of at‑the‑money straddles, which combine a call and a put with the same strike and expiration....
Client research
Register free or login to read the full report
Registration is free. The full report includes chart snapshots, level work, technical tables, catalyst context, and the complete desk read.
Chat with XTRSK
Chat ready
Start a chat and the XTRSK team will be notified immediately.